APAC Data Center Colocation Market – Industry Outlook & Forecast 2026-2031


APAC Data Center Colocation Market – Industry Outlook & Forecast 2026-2031
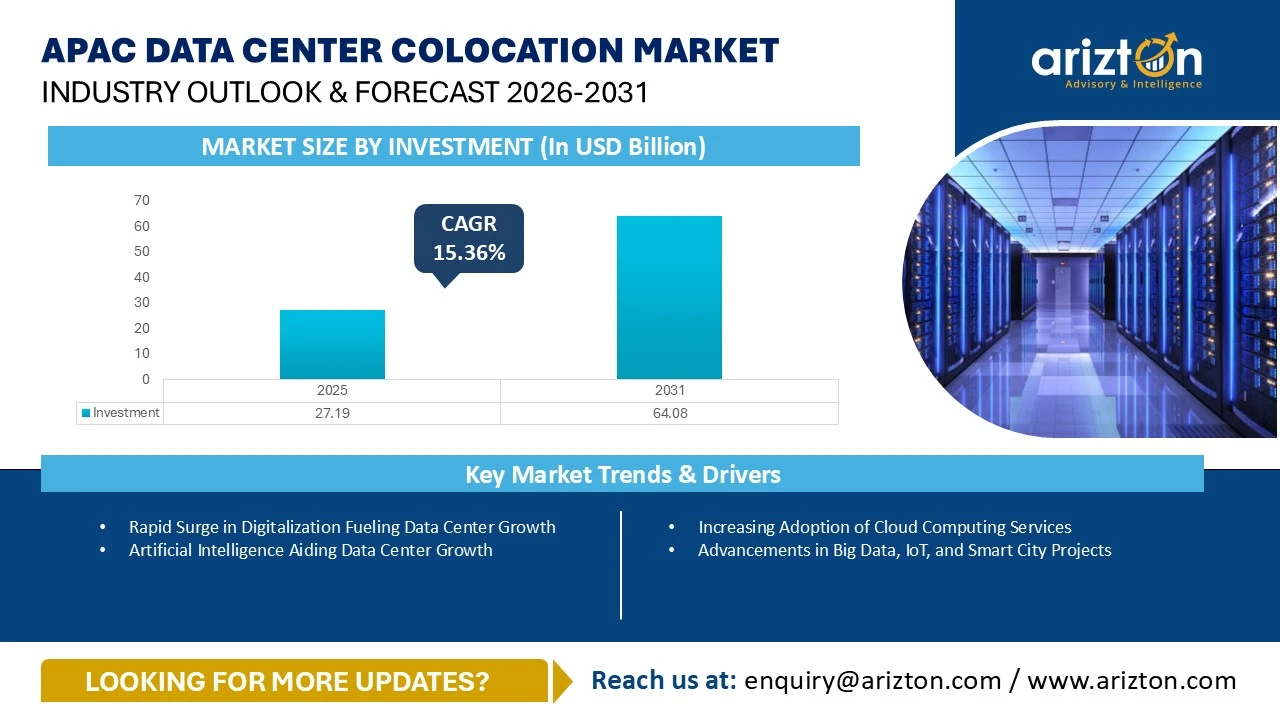
APAC DATA CENTER COLOCATION MARKET SIZE BY INVESTMENT WAS VALUED AT USD 27.19 BILLION IN 2025 AND IS EXPECTED TO REACH USD 64.08 BILLION BY 2031, GROWING AT A CAGR OF 15.36% DURING THE FORECAST PERIOD.
The APAC Data Center Colocation Market Report Includes
- Colocation Type: Retail Colocation and Wholesale Colocation
- Infrastructure: Electrical Infrastructure, Mechanical Infrastructure, and General Construction
- Electrical Infrastructure: UPS Systems, Generators, Transfer Switches & Switchgear, PDUs, and Other Electrical Infrastructure
- Mechanical Infrastructure: Cooling Systems, Racks, and Other Mechanical Infrastructure
- Cooling Systems: CRAC & CRAH Units, Chiller Units, Cooling Towers, Condensers & Dry Coolers, Economizers & Evaporative Coolers, and Other Cooling Units
- Cooling Techniques: Air-based Cooling and Liquid-based Cooling
- General Construction: Core & Shell Development, Installation & Commissioning Services, Engineering & Building Design, Fire Detection & Suppression, Physical Security, and DCIM/BMS Solutions
- Tier Standard: Tier I & II, Tier III, and Tier IV
- Geography: APAC (China, Hong Kong, Australia, New Zealand, Japan, India, South Korea, Taiwan, & Rest of APAC) and Southeast Asia (Singapore, Indonesia, Malaysia, Thailand, Philippines, Vietnam, & Rest of Southeast Asia)
Get Insights on 870 Existing Data Center Facilities and 905 Upcoming Facilities across Asia Pacific
This report includes market data points, ranging from trend
analyses to market estimates & forecasts that you can customize
APAC DATA CENTER COLOCATION MARKET REPORT SCOPE
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| MARKET SIZE BY INVESTMENT (2031) | USD 64.08 Billion |
| MARKET SIZE BY INVESTMENT (2025) | USD 27.19 Billion |
| CAGR - INVESTMENT (2025-2031) | 15.36% |
| MARKET SIZE - COLOCATION REVENUE (2031) | USD 69.78 Billion |
| MARKET SIZE AREA (2031) | 23.80 million sq. feet |
| POWER CAPACITY (2031) | 6,177 MW (2031) |
| BASE YEAR | 2025 |
| FORECAST YEAR | 206-2031 |
| MARKET SEGMENTS | Colocation Service, Infrastructure, Electrical Infrastructure, Mechanical Infrastructure, Cooling Systems, Cooling Techniques, General Construction, Tier Standards, and Geography |
| GEOGRAPHICAL ANALYSIS | APAC (China, Hong Kong, Australia, New Zealand, Japan, India, South Korea, Taiwan, & Rest of APAC) and Southeast Asia (Singapore, Indonesia, Malaysia, Thailand, Philippines, Vietnam, & Rest of Southeast Asia) |
ASIA-PACIFIC DATA CENTER COLOCATION MARKET - SIZE & SHARE ANALYSIS
The APAC data center colocation market was valued at USD 27.19 billion in 2025 and is projected to reach USD 64.08 billion by 2031, growing at a CAGR of 15.36% from 2025 to 2031.
The market is expanding significantly due to several factors, such as the adoption of Artificial Intelligence (AI) and the demand for edge computing. China accounted for a share of around 37% of the APAC data center colocation market investments in 2025, with Southeast Asia contributing approximately 21% to the region’s data center colocation market investments during the same period. Hyperscalers, AI workloads, and a wave of digital-first economies are driving an unprecedented surge in demand for secure, scalable infrastructure across the region.
The data center colocation market in the APAC region is registering fast growth worldwide, fueled by rising cloud adoption, the expansion of edge computing, and the increasing use of technologies such as AI, big data, and IoT.
From China's province-level mega-campuses to Southeast Asia's fast-emerging hubs in Malaysia, Indonesia, and Vietnam, operators and investors are racing to claim a position in one of the world's highest-growth infrastructure sectors. This report gives you the data, competitive intelligence, and forward-looking forecasts to navigate it — covering 870 existing facilities, 905 upcoming projects, 174 companies, and 9 market segments across 17 countries.
Whether you're a colocation provider benchmarking your strategy, a hyperscaler scouting expansion markets, or an investor evaluating the next wave of digital infrastructure plays — this is the definitive market map for APAC data center colocation through 2031.
APAC DATA CENTER COLOCATION MARKET OPPORTUNITIES & TRENDS
Rapid Surge in Digitalization Fueling Data Center Growth
- In 2025, we observe that the APAC nations are experiencing rapid digital transformation, which is reshaping the region’s economy and driving the demand for data center development across the region. The rapid expansion of cloud computing, e-commerce, fintech, artificial intelligence, and other digital services is rapidly increasing data generation and storage needs, creating a strong demand for secure, high-performance, low-latency infrastructure.
- As organizations continue to adopt digital services, the demand for real-time data processing is accelerating, and data centers are becoming more crucial to support APAC’s digital economy. Therefore, with the surge in digitalization across the APAC countries, the demand for data centers will continuously increase during the forecast period.
- In January 2025, the South Korean Ministry of Science and ICT planned to establish a joint project worth approximately $30 million with the Association of Southeast Asian Nations (ASEAN) to promote digital transformation across South Korea and ASEAN by 2029.
Artificial Intelligence Aiding Data Center Growth
- The governments across APAC nations are increasingly focusing on AI development as well as encouraging public and private organizations to adopt AI applications to enhance their operational efficiency and boost productivity.
- In November 2025, the government of Taiwan announced the allocation of around $3.2 million to build a strong AI infrastructure in Taiwan in the process of becoming a global AI leader by 2040. Additionally, this initiative focuses on three main technologies: photonics, quantum computing, and AI robotics.
- APAC is boosting the development of AI with various initiatives, such as focusing on the development of AI-ready data centers, increasing government support, and promoting the adoption of AI across various industries, including healthcare, finance, and technology, to enhance digital transformation and sustainability.
Rise in Adoption of Liquid Cooling Techniques in Data Centers
- In the APAC region, most data centers use traditional air-cooling technologies; however, some facilities have adopted liquid cooling technologies. Liquid cooling is more effective than traditional cooling technologies owing to its higher efficiency and lower energy costs compared with traditional air-cooling technologies.
- In November 2025, Princeton Digital Group started the construction of JC3, a new data center campus, in Jakarta. The data center buildings on the campus will support both liquid and air-cooling solutions.
- We observe that the adoption of liquid cooling in APAC is in the initial phase, and we believe that the demand for liquid cooling will increase across the APAC countries during the upcoming years.
Government Initiatives Driving Data Center Investments
- The governments across APAC countries are promoting data center growth through different initiatives, such as investing in AI infrastructure, offering tax incentives for data center operators, and providing financial support for data center companies.
- In March 2025, the government established the Data Center Task Force (DCTF) to strengthen and regulate the nation’s data center industry. This initiative, co-chaired by the Minister of Investment, Trade and Industry as well as the Minister of Digital, highlights Malaysia’s commitment to building a sustainable digital future. The DCTF is tasked with formulating key policy decisions, enhancing coordination among industry stakeholders, and developing strategic measures to support the continued growth of the country’s data center sector.
APAC DATA CENTER COLOCATION MARKET SEGMENTATION INSIGHTS
- Data center operators in the APAC region are making significant efforts to adopt various sustainability practices in their data center operations. Companies are integrating renewable energy to power their data center operations, replacing lead-acid UPS systems with lithium-ion batteries and diesel generators with HVO-powered generators, as well as installing advanced liquid cooling technologies in data centers to reduce electricity consumption, thereby lowering the environmental impact of data centers and greenhouse gas emissions.
- The adoption of the liquid cooling technique is emerging as a key trend in the APAC data center market, driven by the rapidly rising rack power densities. According to insights from NEXTDC, Vertiv, and NVIDIA, the average data center rack densities are expected to grow from approximately 15–25 kW to over 50 kW by 2029. As AI workloads intensify, peak rack densities are projected to reach 250–500 kW, making traditional air cooling insufficient and accelerating the shift toward liquid cooling techniques.
- Digital Realty installed liquid-cooled servers in its SIN11 data center in Singapore. This reduces power consumption by up to 29%.
APAC DATA CENTER COLOCATION MARKET - REGIONAL ANALYSIS
- In the APAC data center colocation market, China is expected to have the largest APAC data center colocation market share in 2031 in terms of investment, followed by Japan, Australia, Malaysia, and India, among others.
- In China, provinces such as Fujian, Guangdong, Guizhou, Hainan, Hebei, Hunan, Ningxia, Shandong, and Shanghai are some of the primary hubs in China for the development of data centers. In recent years, Jiangsu, Anhui, Guangxi, Inner Mongolia, Sichuan, Shaanxi, and Zhejiang have gained momentum for data center development in China.
- In Hong Kong, Tseung Kwan O remains one of the key locations witnessing substantial growth in data center capacity, with major operators such as SUNeVision Holdings (iAdvantage), Digital Realty, Global Switch, and Telehouse expanding their presence. The area continues to attract strong investment driven by the rising demand for cloud adoption, colocation, and digital infrastructure.
- In Australia, Sydney and Melbourne remained the primary hubs for data center expansion, with major operators such as Equinix, AirTrunk, NEXTDC, Global Switch, Digital Realty, and STACK Infrastructure actively announcing new projects and capacity upgrades.
- Auckland is the major destination that is witnessing rapid data center development in New Zealand, as the city is one of the prominent business hubs in the country, offering lower latency and higher connectivity to support digital services in the country. Other New Zealand cities, including Christchurch, Hamilton, Invercargill, Palmerston, and Wellington, have gained momentum for data center development in the country in recent years.
- In 2025, in terms of data center development in Japan, Tokyo and Osaka are the major locations that witnessed the addition of data center space from operators such as AT TOKYO, Colt Data Centre Services, Digital Edge, Equinix, IDC Frontier, MC Digital Realty, NTT Communications, Telehouse, and AirTrunk
- Mumbai, Navi Mumbai, Hyderabad, Chennai, and Pune are the preferred locations in India, with major investments from colocation service providers such as ST Telemedia Global Data Centres, NTT DATA, CtrlS, Equinix, Sify Technologies, and Airtel (Nxtra Data).
- In South Korea, Seoul is the major center for the development of data centers. In recent years, cities such as Incheon, Bucheon-si, Paju, Pohang, Daegu, Busan, Namyangju, Sejong, Goyang, Jeollanam-do Province, Gyeonggi, Seongnam, Anyang, Gimhae, Cheonan, Daejeon, Cheongju, Gimpo, and Pyeongchon have gained momentum for data center development.
- Taipei is the preferred location in Taiwan, with major investments from data center operators such as Keppel Data Centers, Epoch Digital (Actis), Chunghwa Telecom, Empyrion Digital, SC Zeus Data Centers, and others.
- Singapore is one of the most expensive markets in the world for developing data center facilities. In addition, land availability for data center development is very limited. Operators continue to purchase industrial plots to convert into data centers; however, such activities remain relatively low in the market.
- Jakarta is the preferred location in Indonesia, with major investments from colocation service providers such as ST Telemedia Global Data Centres, EdgeConneX, Princeton Digital Group, NTT DATA, DAMAC Digital, and MettaDC.
- Cyberjaya is the most established and preferred hub for data centers in Malaysia; it is known for its robust power infrastructure, connectivity, and government support. It hosts major players such as AIMS Data Centre, Bridge Data Centres, Telekom Malaysia, and NTT DATA, making it the primary data center cluster of the country.
- Thailand offers foreign ownership flexibility, access to pre-approved energy and fiber infrastructure, as well as various incentives through its EEC, which makes it the perfect location to invest in Southeast Asia. Bangkok is the preferred location in Thailand, with major investments from colocation service providers such as ST Telemedia Global Data Centres, AIS Business (CSL), OneAsia Network, True IDC, Internet Thailand, Telehouse, and SUPERNAP Thailand.
- Manila remains the primary data center hub in the Philippines, accounting for the largest concentration of operational facilities in the Philippines.
- Hanoi and Ho Chi Minh City are the most preferred locations for data center operators in Vietnam. Hanoi accounts for the highest number of data center facilities in the country.
DATA CENTER COLOCATION MARKET VENDORS IN APAC
- In 2025, the APAC data center colocation market is driven by major colocation operators such as, China Telecom, China Mobile, China Unicom, Equinix, GDS Services, Chindata Group, AirTrunk, VNET, NTT DATA, ST Telemedia Global Data Centres, Digital Realty, CDC Data Centres, CDC Data Centres, SUNeVision Holdings, LG Uplus, NEXTDC, Shanghai Atrium, Nxera (Singtel), CtrlS Datacenters, Keppel Data Centres, Sify Technologies, Telkom Indonesia, and DCI Indonesia.
- In 2025, the growing demand from customers across various verticals, especially cloud service providers, as well as the increasing digitalization efforts by private and public sector organizations across the region, is set to propel the entry of several new investors. New entrants include AM Green Group, Aqylon Nexus, AREA Group of Companies, Asia Pacific Land, BW DIGITAL, Chinachem Group, CloudHQ, CURRENC Group, CyrusOne, Daewoo Engineering & Construction, DAMAC Digital, Data Center First, DC Connects, Doma Infrastructure Group, Diode Ventures, Endec, ESR, Everstone Group, Evolution Data Centres, FIR HILLS, FLOW Digital Infrastructure, FutureData, Global Telecommunications, GreenSquareDC, Haoyang Data, i-Berhad, Trifalga, and ZDATA Group.
- In terms of colocation revenue, China Telecom dominated the APAC data center colocation market in 2025. China Telecom was followed by China Mobile, China Unicom, GDS Services, Equinix, AirTrunk, among others.
SNAPSHOT
The APAC data center colocation market by investment is projected to reach USD 64.08 billion by 2031, growing at a CAGR of 15.36% from 2025 to 2031.
The following factors are likely to contribute to the growth of the APAC data center colocation market during the forecast period:
- Increasing Adoption of Cloud Computing Services
- Advancements in Big Data, IoT, and Smart City Projects
- Surge in Submarine Cable Connectivity Fuelling Data Center Growth
- Increasing Joint Ventures in the Market
- Adoption of Sustainability Measures among Data Center Operators
Base Year: 2025
Forecast Year: 2026-2031
The report considers the present scenario of the APAC data center colocation market and its market dynamics for 2026−2031. It covers a detailed overview of several market growth enablers, restraints, and trends. The study includes the demand and supply aspects of the APAC data center colocation industry.
Prominent Colocation Operators
- AirTrunk
- CDC
- China Mobile International
- China Telecom Corporation
- China Unicom
- Chindata Group
- Digital Realty
- Equinix
- GDS Holdings
- Keppel Data Centres
- NEXTDC
- NTT DATA
- Princeton Digital Group
- ST Telemedia Global Data Centres
- Telkom Indonesia
- Vantage Data Centers
Other Prominent Colocation Operators
- AdaniConneX
- A-FLOW
- AIMS Data Centre
- Anant Raj Cloud Data Center
- Athub
- @Tokyo
- BDx Data Centers
- Beeinfotech PH
- Beijing Sinnet Technology
- BRIGHTRAY
- BSNL
- CapitaLand
- CAT Telecom Public Company
- Centuria Capital Group
- Chayora
- Chief Telecom
- Chunghwa Telecom
- CMC Telecom
- Colt Data Centre Services
- Converge ICT Solutions
- CtrlS Datacenters
- DayOne
- DCI Data Centers
- DCI Indonesia
- Digital Edge DC
- Digital Halo
- DITO Telecommunity
- Dr. Peng Telecom & Media Group
- EdgeConneX
- Empyrion Digital
- ePLDT
- Epoch Digital
- ESDS Software Solution
- Etix Everywhere
- FPT Telecom
- Fujitsu
- Gaw Capital
- Global Switch
- Goodman
- GSA DATA CENTER
- Hotwon Network Group
- Internet Initiative Japan
- Iron Mountain
- iTech Towers Data Centre Services
- KORAMCO Asset Management
- KT Corp
- LG CNS
- LG Uplus
- Macquarie Data Centres
- Mapletree
- MettaDC
- Nxera
- Nxtra by Airtel
- OneAsia Network
- Open DC
- Pi Data Centers
- Pure Data Centres Group
- RackBank
- Racks Central
- RailTel Corporation of India
- Reliance Jio
- Samsung SDS
- Secom Trust Systems
- Sify Technologies
- SK Broadband
- SK ecoplant
- SKYY Development,
- SM+
- ST Engineering
- STACK Infrastructure,
- SUNeVision Holdings
- T4 NZ Data Centres
- Techno Electric & Engineering Company (TEECL)
- Telehouse
- Tenglong Holding Group
- VADS Berhad
- TenPeaks Data Centres
- True Internet Data Center (True IDC)
- Viettel IDC
- VNET Group
- VNPT
- VNTT
- YCO Cloud
- Yondr Group
- Yotta Data Services
- YTL Data Center
- Ada Infrastructure
New Entrants
- AIZO Group Berhad
- AM Green Group
- Aqylon Nexus
- AREA Group Of Companies
- Asia Pacific Land (APL)
- Aslan Energy Capital (AEC)
- BW DIGITAL
- Changhae Development
- Chinachem Group (CCG)
- CloudHQ
- Create Capital Viet Nam Joint-stock Company + haymaker+ Vietnam Data Gen
- CURRENC Group
- CyrusOne
- Da Nang International Data Centre Joint Stock Company (JSC),
- Daewoo Engineering & Construction
- DAMAC Digital
- Data Center First
- Datagrid New Zealand
- DC Connects
- Doma Infrastructure Group
- Dongyang
- Diode Ventures
- Endec,
- ESR
- Everstone Group
- Evolution Data Centres
- FIR HILLS
- FLOW Digital Infrastructure
- FutureData
- GIBO Holdings
- GigaStream Toyama
- Global Telecommunications
- GreenSquareDC
- Haoyang Data
- Henox IT And Datacenters
- Hyosung Corporation
- i-Berhad
- IGIS Asset Management
- Infracrowd Capital
- Inuverse
- ISPT
- IPTP Networks
- Kakao Corp.
- KinhBacCity Group (KBC)
- KOSCOM
- Lehr Consultants International (LCI Consultants)
- LG Electronics, KEPKO, & Hanwha Corporation E&C Division’s
- MaNaDr Mobile Health
- THOMSON Computing – METAVISIO
- MARKHAM
- Megaspeed AI
- MyTelehaus
- Nautilus Data Technologies
- NES DATA
- OKESTRO
- Perri Group
- Supernode by Quinbrook Infrastructure Partners
- Rovision Tech Hub
- Siagon Asset Management
- Saigontel
- SC Zeus Data Centers
- SEAX Global
- SGC Energy
- Stellar DC
- Tata Consultancy Services & OpenAI’s
- Toyota Tsusho Corporation
- TPG Angelo Gordon
- Trifalga
- UPC Volt
- ZDATA Group
- Zr Power Holdings
Segmentation by Colocation Type
- Retail Colocation
- Wholesale Colocation
Segmentation by Infrastructure
- Electrical Infrastructure
- Mechanical Infrastructure
- General Construction
Segmentation by Electrical Infrastructure
- UPS Systems
- Generators
- Transfer Switches & Switchgear
- PDUs
- Other Electrical Infrastructure
Segmentation by Mechanical Infrastructure
- Cooling Systems
- Racks
- Other Mechanical Infrastructure
Segmentation by Cooling Systems
- CRAC & CRAH Units
- Chiller Units
- Cooling Towers, Condensers & Dry Coolers
- Economizers & Evaporative Coolers
- Other Cooling Units
Segmentation by Cooling Techniques
- Air-based Cooling
- Liquid-based Cooling
Segmentation by General Construction
- Core & Shell Development
- Installation & Commissioning Services
- Engineering & Building Design
- Fire Detection & Suppression
- Physical Security
- DCIM/BMS Solutions
Segmentation by Tier Standard
- Tier I & II
- Tier III
- Tier IV
Segmentation by Geography
- APAC
- China
- Hong Kong
- Australia
- New Zealand
- Japan
- India
- South Korea
- Taiwan
- Rest of APAC
- Southeast Asia
- Singapore
- Indonesia
- Malaysia
- Thailand
- Philippines
- Vietnam
- Other Southeast Asian Countries
APAC DATA CENTER COLOCATION MARKET FAQs
How big is the APAC data center colocation market?
What is the growth rate of the APAC data center colocation market?
What are the key trends in the APAC data center colocation market?
What is the estimated market size in terms of area in the APAC data center colocation market by 2031?
How much MW of power capacity is expected to reach the APAC data center colocation market by 2031?
What are the key trends in the APAC data center colocation market?
What is the growth rate of the APAC data center colocation market?
For more details, please reach us at [email protected]
1. ABOUT ARIZTON
2. ABOUT OUR DATA CENTER CAPABILITIES
3. WHAT’S INCLUDED
4. SEGMENTS INCLUDED
5. RESEARCH METHODOLOGY
6. MARKET AT GLANCE
7. PREMIUM INSIGHTS
8. INTRODUCTION
9. APAC DATA CENTER COLOCATION MARKET OVERVIEW
10. APAC DATA CENTER COLOCATION MARKET LANDSCAPE
11. APAC DATA CENTER COLOCATION MARKET VENDOR ANALYSIS
12. APAC DATA CENTER COLOCATION MARKET OVERVIEW
13. DATA CENTER FINANCING
14. GREEN DATA CENTER FINANCING
15. INVESTMENT OPPORTUNITIES
15.1. INVESTMENT: MARKET SIZE & FORECAST
15.2. AREA: MARKET SIZE & FORECAST
15.3. POWER CAPACITY: MARKET SIZE & FORECAST
15.4. COLOCATION REVENUE: MARKET SIZE & FORECAST
16. MARKET DYNAMICS
16.1. MARKET OPPORTUNITIES & TRENDS
16.2. MARKET GROWTH ENABLERS
16.3. MARKET RESTRAINTS
16.4. SITE SELECTION CRITERIA
17. INFRASTRUCTURE SEGMENTATION
17.1. MARKET SEGMENTATION
17.2. COLOCATION SERVICE
17.3. ELECTRICAL INFRASTRUCTURE
17.4. MECHANICAL INFRASTRUCTURE
17.5. COOLING SYSTEMS
17.6. COOLING TECHNIQUES
17.7. GENERAL CONSTRUCTION
18. TIER STANDARDS SEGMENTATION
19. GEOGRAPHY SEGMENTATION
20. MARKET BY GEOGRAPHY
21. APAC
21.1. MARKET SNAPSHOT & KEY HIGHLIGHTS
21.2. DATA CENTER MARKET BY SUPPORT INFRASTRUCTURE
22. CHINA
22.1. IMPACT OF AI ON THE DATA CENTER INDUSTRY IN CHINA
22.2. GOVERNMENT RULE AND REGULATION FOR DATA CENTER
22.3. MARKET BY INVESTMENT
22.4. MARKET BY AREA
22.5. MARKET BY POWER CAPACITY
22.6. COLOCATION REVENUE
22.7. KEY SUPPORT INFRASTRUCTURE ADOPTION
22.8. LIST OF UPCOMING DATA CENTER PROJECTS IN CHINA
23. HONG KONG
23.1. IMPACT OF AI ON THE DATA CENTER INDUSTRY IN HONG KONG
23.2. GOVERNMENT RULE AND REGULATION FOR DATA CENTER
23.3. MARKET BY INVESTMENT
23.4. MARKET BY AREA
23.5. MARKET BY POWER CAPACITY
23.6. COLOCATION REVENUE
23.7. KEY SUPPORT INFRASTRUCTURE ADOPTION
23.8. LIST OF UPCOMING DATA CENTER PROJECTS IN HONG KONG
24. AUSTRALIA
24.1. IMPACT OF AI ON THE DATA CENTER INDUSTRY IN AUSTRALIA
24.2. GOVERNMENT RULE AND REGULATION FOR DATA CENTER
24.3. MARKET BY INVESTMENT
24.4. MARKET BY AREA
24.5. MARKET BY POWER CAPACITY
24.6. COLOCATION REVENUE
24.7. KEY SUPPORT INFRASTRUCTURE ADOPTION
24.8. LIST OF UPCOMING DATA CENTER PROJECTS IN AUSTRALIA
25. NEW ZEALAND
25.1. IMPACT OF AI ON THE DATA CENTER INDUSTRY IN NEW ZEALAND
25.2. GOVERNMENT RULE AND REGULATION FOR DATA CENTER
25.3. MARKET BY INVESTMENT
25.4. MARKET BY AREA
25.5. MARKET BY POWER CAPACITY
25.6. COLOCATION REVENUE
25.7. KEY SUPPORT INFRASTRUCTURE ADOPTION
25.8. LIST OF UPCOMING DATA CENTER PROJECTS IN NEW ZEALAND
26. JAPAN
26.1. IMPACT OF AI ON THE DATA CENTER INDUSTRY IN JAPAN
26.2. GOVERNMENT RULE AND REGULATION FOR DATA CENTER
26.3. MARKET BY INVESTMENT
26.4. MARKET BY AREA
26.5. MARKET BY POWER CAPACITY
26.6. COLOCATION REVENUE
26.7. KEY SUPPORT INFRASTRUCTURE ADOPTION
26.8. LIST OF UPCOMING DATA CENTER PROJECTS IN JAPAN
27. INDIA
27.1. IMPACT OF AI ON THE DATA CENTER INDUSTRY IN INDIA
27.2. GOVERNMENT RULE AND REGULATION FOR DATA CENTER
27.3. MARKET BY INVESTMENT
27.4. MARKET BY AREA
27.5. MARKET BY POWER CAPACITY
27.6. COLOCATION REVENUE
27.7. KEY SUPPORT INFRASTRUCTURE ADOPTION
27.8. LIST OF UPCOMING DATA CENTER PROJECTS IN INDIA
28. SOUTH KOREA
28.1. IMPACT OF AI ON THE DATA CENTER INDUSTRY IN SOUTH KOREA
28.2. GOVERNMENT RULE AND REGULATION FOR DATA CENTER
28.3. MARKET BY INVESTMENT
28.4. MARKET BY AREA
28.5. MARKET BY POWER CAPACITY
28.6. COLOCTION REVENUE
28.7. KEY SUPPORT INFRASTRUCTURE ADOPTION
28.8. LIST OF UPCOMING DATA CENTER PROJECTS IN SOUTH KOREA
29. TAIWAN
29.1. IMPACT OF AI ON THE DATA CENTER INDUSTRY IN TAIWAN
29.2. GOVERNMENT RULE AND REGULATION FOR DATA CENTER
29.3. MARKET BY INVESTMENT
29.4. MARKET BY AREA
29.5. MARKET BY POWER CAPACITY
29.6. COLOCATION REVENUE
29.7. KEY SUPPORT INFRASTRUCTURE ADOPTION
29.8. LIST OF UPCOMING DATA CENTER PROJECTS IN TAIWAN
30. REST OF APAC
30.1. MARKET BY INVESTMENT
30.2. MARKET BY AREA
30.3. MARKET BY POWER CAPACITY
30.4. COLOCATION REVENUE
30.5. KEY SUPPORT INFRASTRUCTURE ADOPTION
31. SOUTHEAST ASIA
31.1. MARKET SNAPSHOT & KEY HIGHLIGHTS
31.2. DATA CENTER MARKET BY SUPPORT INFRASTRUCTURE
32. SINGAPORE
32.1. IMPACT OF AI ON THE DATA CENTER INDUSTRY IN SINGAPORE
32.2. GOVERNMENT RULE AND REGULATION FOR DATA CENTER
32.3. MARKET BY INVESTMENT
32.4. MARKET BY AREA
32.5. MARKET BY POWER CAPACITY
32.6. COLOCATION REVENUE
32.7. KEY SUPPORT INFRASTRUCTURE ADOPTION
32.8. LIST OF UPCOMING DATA CENTER PROJECTS IN SINGAPORE
33. INDONESIA
33.1. IMPACT OF AI ON THE DATA CENTER INDUSTRY IN INDONESIA
33.2. GOVERNMENT RULE AND REGULATION FOR DATA CENTER
33.3. MARKET BY INVESTMENT
33.4. MARKET BY AREA
33.5. MARKET BY POWER CAPACITY
33.6. COLOCATION REVENUE
33.7. KEY SUPPORT INFRASTRUCTURE ADOPTION
33.8. LIST OF UPCOMING DATA CENTER PROJECTS IN INDONESIA
34. MALAYSIA
34.1. IMPACT OF AI ON THE DATA CENTER INDUSTRY IN MALAYSIA
34.2. GOVERNMENT RULE AND REGULATION FOR DATA CENTER
34.3. MARKET BY INVESTMENT
34.4. MARKET BY AREA
34.5. MARKET BY POWER CAPACITY
34.6. COLOCATION REVENUE
34.7. KEY SUPPORT INFRASTRUCTURE ADOPTION
34.8. LIST OF UPCOMING DATA CENTER PROJECTS IN MALAYSIA
35. THAILAND
35.1. IMPACT OF AI ON THE DATA CENTER INDUSTRY IN THAILAND
35.2. GOVERNMENT RULE AND REGULATION FOR DATA CENTER
35.3. MARKET BY INVESTMENT
35.4. MARKET BY AREA
35.5. MARKET BY POWER CAPACITY
35.6. COLOCATION REVENUE
35.7. KEY SUPPORT INFRASTRUCTURE ADOPTION
35.8. LIST OF UPCOMING DATA CENTER PROJECTS IN THAILAND
36. PHILIPPINES
36.1. IMPACT OF AI ON THE DATA CENTER INDUSTRY IN PHILIPPINES
36.2. GOVERNMENT RULE AND REGULATION FOR DATA CENTER
36.3. MARKET BY INVESTMENT
36.4. MARKET BY AREA
36.5. MARKET BY POWER CAPACITY
36.6. COLOCATION REVENUE
36.7. KEY SUPPORT INFRASTRUCTURE ADOPTION
36.8. LIST OF UPCOMING DATA CENTER PROJECTS IN PHILIPPINES
37. VIETNAM
37.1. IMPACT OF AI ON THE DATA CENTER INDUSTRY IN VIETNAM
37.2. GOVERNMENT RULE AND REGULATION FOR DATA CENTER
37.3. MARKET BY INVESTMENT
37.4. MARKET BY AREA
37.5. MARKET BY POWER CAPACITY
37.6. COLOCATION REVENUE
37.7. KEY SUPPORT INFRASTRUCTURE ADOPTION
37.8. LIST OF UPCOMING DATA CENTER PROJECTS IN VIETNAM
38. REST OF SOUTHEAST ASIA
38.1. MARKET BY INVESTMENT
38.2. MARKET BY AREA
38.3. MARKET BY POWER CAPACITY
38.4. COLOCATION REVENUE
38.5. KEY SUPPORT INFRASTRUCTURE ADOPTION
39. COMPETITIVE LANDSCAPE
39.1. MARKET SHARE BY COLOCATION INVESTMENT
39.2. MARKET SHARE BY COLOCATION AREA
39.3. MARKET SHARE BY COLOCATION POWER CAPACITY
39.4. MARKET SHARE BY COLOCATION REVENUE
40. MARKET PARTICIPANTS
40.1. PROMINENT COLOCATION OPERATORS
40.2. OTHER PROMINENT COLOCATION OPERATORS
40.3. NEW ENTRANTS
41. QUANTITATIVE SUMMARY
42. APPENDIX
42.1. ABBREVIATIONS
42.2. DEFINITIONS
42.3. SEGMENTAL COVERAGE
Select a license type that suits your business needs
Single User Licence
- Report accessible by one user only
- Free 10% or 3 days of customization
- Free post-sale service assistance
- Continuous support through email
5 User Licence
- Report accessible by 5 users within the organization
- Free 15% or 4.5 days of customization
- Continuous support through email and telephone
- Free analyst hour
- Free Upgrade: If an updated report published within 180 days of purchase, you will get the revised report free of charge
Corporate Licence
- Free Datasheet worth $1500
- Report accessible by the entire organization
- Free 20% or 6 days of customization
- Free post-sale service assistance
- Continuous support through email and telephone
- Direct access to lead analysts
- Free analyst hour
- Free Upgrade: If an updated report published within 180 days of purchase, you will get the revised report free of charge
Datasheet Licence
- Report accessible by 1 user only
- Free 15% or 32 hours of customization
- Free post-sale service assistance
- Direct access to lead analysts
Frequently Asked Questions
How big is the APAC data center colocation market?
What is the growth rate of the APAC data center colocation market?
What are the key trends in the APAC data center colocation market?
What is the estimated market size in terms of area in the APAC data center colocation market by 2031?
How much MW of power capacity is expected to reach the APAC data center colocation market by 2031?
What are the key trends in the APAC data center colocation market?
What is the growth rate of the APAC data center colocation market?
Other RELATED Reports
Latin America Data Center Colocation Market – Industry Outlook & Forecast 2026-2031
Published : June 2026
Southeast Asia Data Center Colocation Market – Industry Outlook & Forecast 2026-2031
Published : June 2026
Middle East Data Center Colocation Market – Industry Outlook & Forecast 2025-2030
Published : November 2025
Europe Data Center Colocation Market – Industry Outlook & Forecast 2025-2030
Published : January 2026