APAC data centers: Track at the facility level, covering operational sites, physical infrastructure, upcoming projects, investment pipelines, capacity additions, operators, locations, and colocation pricing across 16 key countries and markets.
Published Date : June 2026
Last Updated : October 2026
format: PDF
edition : Ninth Edition
946 Existing Data Centers
527 Upcoming Data Centers
334 Data Center Operators
13 No. of Cities
Purchase Options
APAC Existing & Upcoming Data Center Portfolio
DISCOVER INSIGHTS ON 1473 DATA CENTER FACILITIES ACROSS 16 KEY COUNTRIES IN APAC
Existing & Upcoming Data Centers in APAC: Facility-Level Capacity, Operators, Investments & Colocation Intelligence
The APAC Data Center Portfolio provides detailed facility-level intelligence on the region’s existing and upcoming data center infrastructure, helping businesses assess operational capacity, monitor development pipelines, and compare activity across individual markets.
- 946 existing data centers
- 527 upcoming data centers
- 334 data center operators and investors
- 16 countries and markets covered: Australia, Bangladesh, Hong Kong, India, Indonesia, Japan, Malaysia, Nepal, New Zealand, Pakistan, Philippines, Singapore, South Korea, Taiwan, Thailand, and Vietnam.
- White-floor area, IT load, and rack capacity
- Project investment, development status, and expected opening timelines
- Retail and wholesale colocation pricing
This report includes market data points, ranging from trend
analyses to market estimates & forecasts that you can customize
APAC DATA CENTERS
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Total facilities profiled | 1,473 |
| Existing Data Centers | 946 |
| Upcoming Data Centers | 527 |
| Data center Operators & investors in APAC | 334 |
| Countries covered | 16 |
| Upcoming Data Center IT capacity | 700 MW–8.3 GW (Vietnam, Philippines, Thailand & Malaysia) |
| Facility-Level Capacity | White-floor area, IT load, and rack capacity |
| Project Intelligence | Investment, status, and opening timelines |
| Colocation Pricing | Retail & wholesale |
APAC DATA CENTERS
Asia-Pacific is a diverse data center market, bringing together established hubs such as Australia, Japan, India, and South Korea with rapidly expanding markets across Southeast Asia.
The APAC Data Center Portfolio profiles 1,473 facilities, including 946 existing and 527 upcoming data centers, across 16 countries and markets. It covers facility capacity, infrastructure characteristics, operators, investment, development status, geographic distribution, and colocation pricing.
The database helps users compare mature data center markets with emerging locations where new infrastructure is being planned and developed.
DATA CENTERS IN APAC - AT A GLANCE
- 946 existing data centers are tracked across the region.
- 527 upcoming facilities are included in the development pipeline.
- 334 operators and investors are covered.
- Australia leads the existing market, with more than 2.1 GW of power capacity.
- India, Australia, Malaysia, and South Korea collectively account for more than 70% of upcoming power capacity in the region.
- Vietnam, the Philippines, Thailand, and Malaysia are attracting significant development activity, with upcoming capacity varying by market.
- The regional landscape spans established cloud and colocation hubs as well as new markets seeking to expand digital infrastructure.
DATA CENTER FACILITIES IN APAC
The APAC Data Center Portfolio goes beyond a basic list of facilities by tracking the physical, technical, commercial, and development characteristics of individual data centers.
For existing facilities, the database captures location, address, operator/owner, facility name, white-floor area, IT load capacity, rack capacity, year of operation, Tier standard, and power/cooling redundancy.
For upcoming projects, it tracks investor, location, planned area, IT load, total investment, infrastructure investment split, announcement year, project status, and expected opening year.
This facility-level structure supports comparisons across markets, operators, individual assets, and development pipelines. The existing-facility database excludes data center facilities in China.
EXISTING DATA CENTERS IN APAC
Operational facilities with capacity and infrastructure details: The existing facility database covers 946 operational data centers, supporting comparisons of facility scale, capacity, infrastructure design, operator presence, and geographic distribution.
EXISTING FACILITY DATA POINTS
- Market snapshot
- Region, country, and city
- Full facility address
- Operator/owner name
- Data center/facility name
- Core & shell white-floor area
- Core & shell IT load capacity
- Rack capacity
- Year of operation
- Tier I–IV design standard
- Power redundancy
- Cooling/mechanical redundancy
UPCOMING DATA CENTER PROJECTS IN APAC
Track future capacity, investment, and development status: The portfolio tracks 527 upcoming data center facilities, providing visibility into announced, planned, and under-construction projects across the region.
With substantial development activity in India, Australia, Malaysia, South Korea, and other emerging markets, the pipeline offers a structured view of where new capacity is planned and which investors are expanding their presence.
UPCOMING FACILITY DATA POINTS
- Investment snapshot
- Region, country, and city
- Investor name
- Planned white-floor area
- Planned IT load/power capacity
- Total investment
- Electrical infrastructure investment
- Mechanical infrastructure investment
- General construction investment
- Announcement year
- Project status
- Active or expected year of opening
DATA CENTER OPERATORS & CLOUD PROVIDERS IN APAC
The database covers 334 operators and investors active across Asia-Pacific — one of the largest operator counts in any Arizton regional portfolio — from the region's capacity leaders to national telecoms, hyperscale and AI-infrastructure ventures, and hundreds of local and specialist colocation providers.
- Capacity leaders: NEXTDC, CDC Data Centres, AirTrunk, Equinix
- Major regional and global platforms: Digital Realty, NTT Global Data Centers, ST Telemedia Global Data Centres, STACK Infrastructure, Princeton Digital Group, DayOne (GDS Services), Keppel DC REIT, GLP (Ada Infrastructure), Mapletree Investment Trust, Vantage Data Centers
- National telecom and sovereign-backed operators: NTT, KT Cloud, LG Uplus, SK Broadband, Chunghwa Telecom, Telstra, Singtel & Telekom Malaysia, Viettel, VNPT, Chorus, Telkom Indonesia
- Hyperscale and AI-infrastructure ventures: Tata Consultancy Services (TCS) & OpenAI, OpenAI & SK Telecom, Samsung, Samsung SDS, AirTrunk + ByteDance, G42 (UAE) + FPT + VinaCapital
- Newer entrants and specialist developers across the region: AdaniConneX, DCI Data Centers & Koramco, BRIGHTRAY, ZDATA Technologies, Firmus & CDC Data Centres, Yondr Group and Marubeni Corporation.
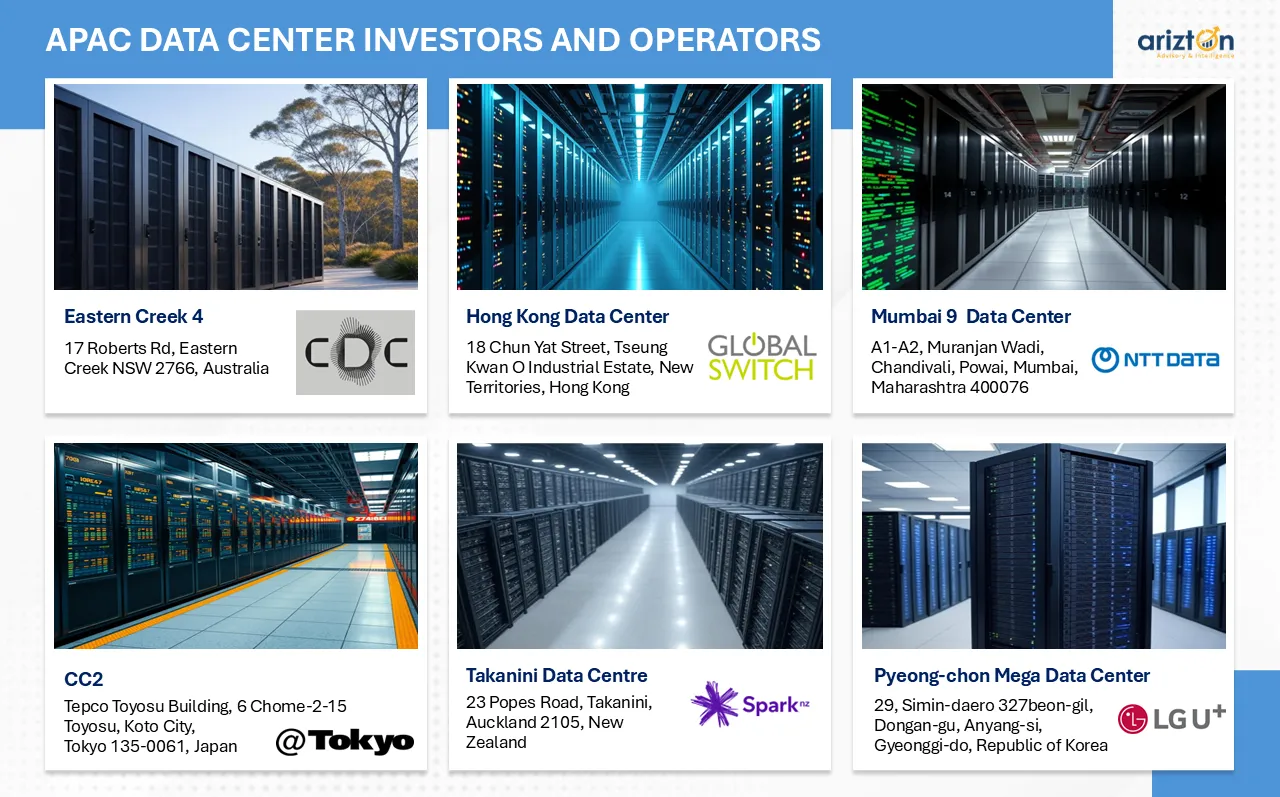
APAC DATA CENTERS - PROJECTS DEVELOPMENT PIPELINE
APAC’s development pipeline reflects both continued expansion in established markets and the emergence of new data center locations.
India, Australia, Malaysia, and South Korea collectively account for more than 70% of upcoming power capacity, according to Arizton’s portfolio overview. Meanwhile, Vietnam, the Philippines, and Thailand are among the markets attracting significant new development activity.
The portfolio tracks upcoming projects at the facility level, linking planned capacity with location, investor, investment estimates, project status, and expected opening timelines. This helps users distinguish between individual projects and assess the development pipeline market by market.
GEOGRAPHIC COVERAGE ACROSS APAC
The portfolio covers 16 countries and markets:
Australia | Bangladesh | Hong Kong | India | Indonesia | Japan | Malaysia | Nepal | New Zealand | Pakistan | Philippines | Singapore | South Korea | Taiwan | Thailand | Vietnam
This geographic coverage supports analysis of:
- Established data center clusters
- Emerging development locations
- Operator expansion patterns
- Regional capacity distribution
- New project activity
- Country-level investment opportunities
- Differences between operational markets and upcoming development pipelines
*The existing facility database does not include China data center facilities.
DATA CENTER CAPACITY & INFRASTRUCTURE
Counting data centers alone does not explain the scale of a market. The database therefore captures three important facility-level capacity indicators:
- White-Floor Area: Understand the physical IT space available or planned at each facility.
- IT Load Capacity: Compare current and planned IT power capacity in MW.
- Rack Capacity: Assess the number of racks supported by individual facilities where available.
Together, these metrics provide a more useful view of data center scale and capacity distribution across APAC. The current portfolio specifically highlights white-floor area, IT load, and rack capacity as core database attributes. Compare current and planned IT power capacity in MW.
INFRASTRUCTURE & RESILIENCY DETAILS
For existing facilities, the database captures Tier standards and power/cooling redundancy, helping users understand differences in facility design and resiliency.
Coverage includes:
- Tier I–IV classification
- Electrical redundancy
- Mechanical/cooling redundancy
- IT load capacity
- Rack capacity
- White-floor area
- Year of operation
APAC DATA CENTER COLOCATION PRICING
The portfolio includes colocation pricing alongside facility and infrastructure information, supporting comparisons across covered markets.
PRICING COVERAGE
- Quarter rack / 1⁄4 rack pricing
- Half rack cabinet pricing
- Full rack cabinet pricing
- Full cabinet configurations such as 42U / 45U / 47U
- Wholesale colocation pricing per kW
This allows users to assess retail rack and wholesale colocation pricing alongside facility capacity, infrastructure, and market location.
WHAT CAN YOU DO WITH THE APAC DATA CENTER PORTFOLIO?
- Identify existing facilities — Build a structured view of operational data centers by country, city, operator, capacity, and infrastructure.
- Track upcoming projects — Monitor announced, planned, and under-construction facilities across the region.
- Compare operators — Benchmark operators by facility footprint, IT capacity, rack capacity, and geographic presence.
- Map new investment — Identify where new capital is being directed and which organizations are expanding.
- Assess regional capacity — Compare existing and upcoming white-floor area, IT load, and rack capacity.
- Evaluate markets — Compare established data center hubs with emerging locations across APAC.
- Benchmark colocation — Use retail and wholesale pricing data to understand commercial conditions across covered markets.
- Support market entry — Identify operators, investors, locations, projects, and potential expansion opportunities.
- Support infrastructure planning — Review facility-level capacity and infrastructure characteristics when assessing potential requirements.
- Monitor competitive activity — Track operator presence and project development across multiple countries.
RESEARCH METHODOLOGY
- Primary sources: data center contractors and subcontractors, system integrators (power, cooling, physical security, fire suppression), developers and infrastructure providers.
- Secondary sources: Arizton monitors 500+ colocation operators across about 50 countries through press releases, annual reports, investor presentations, industry reports, and news.
- Clean counting: phase-wise expansions sit in existing facilities. Ground-up builds sit in upcoming. Campuses count only operational buildings. Capacity colocated inside another provider's facility is not double-counted.
- Actual and estimated values: investment figures blend reported and estimated values, with estimates based on the average data center build cost in APAC.
LIST OF DATA CENTER INVESTORS/OPERATORS IN APAC
(New Era Technology) Intervolve, 5G Networks, AAPT (TPG Telecom), Aboitiz, Acer eDC, AdaniConneX, A-FLOW (Ayala Land and PAG's), AGS Corporation, AIMS Data Centre (DigitalBridge), Airtel (Nxtra), Airtrunk+ ByteDance, AIS Business (CSL), Aizo Group and Netrunner, AkashiQ, AM Green Group (AMG), Anant Raj Cloud Pvt Ltd (ARCPL), AnsonNet, APT Satellite, Aqylon Nexus Limited, Area Group, ARTERIA Networks Corporation, Asia Pacific Land (APL) and Global Compute Infrastructure (GCI), Asia Satellite Telecommunication Company, Aslan Energy Capital, AT TOKYO, Basis Bay, BDx, Beeinfotech, Benzy Infotech Data Center, Bitera Data Center, Bitstop Network Services, Biznet, Blackstone & Panchshil Realty, Bridge Data Centres, BRIGHTRAY, BSNL & NxtGen Datacenter, BW Digital, ByteDC Solutions, C&T + CMC Telecom, Caduceus Systems, Canon IT Solutions, CapitaLand, Carrianna Group, Carrier Connect Data Solutions (Nexion Group), CAT Telecom (National Telecom), CDC Data Centres, Centuria Industrial REIT, Chaktomuk Data Center, Changhae Development, Chief Telecom, China Mobile International, China Unicom, Chinachem Group, Chorus, Chunghwa Telecom, CITIC Telecom International, CloudHQ, CMC Telecom, Colocity, Colt Data Centre Services & ESR joint venture, Computer Concepts Limited (CCL), Converge ICT Solutions Inc., Create Capital Vietnam JSC + Haimaker.ai + Vietnam Data Gen, CSF Group, CTC, CtrlS Datacenters + National Telecom, Cundall Johnston, Currenc Group Inc., Cyber Data International, Cyfuture India, CyrusOne KEP, Da Nang IDC, Daewoo Engineering & Construction, DAMAC Digital, DAOU IDC, Data Center First, Data Centre 220, Data Vault, Datacom Group Ltd, DataGrid, Daun Penh Provider, DayOne (GDS Services), DC Alliance, DC Connect, DC West, DCI Data Centers & Koramco, Digital Connexion (BAM Digital Reality), Digital Edge, Digital Edge DC, Digital Halo, Digital Hyperspace Indonesia, Digital Realty, Digital Sense, Diode Ventures and ENDEC, DITO Telecommunity, Doma Infrastructure Group (DIG), Dongyang (Eugene Group) (Construction to commence 1H 2026), Dreammark1 Corporation, DTP, DTS Telecom, DXN, eASPNet, EasyLink, Edge Centres, EdgeConneX, Elitery Data Center, Empyrion Digital, Enable Networks, Endec Group, ePLDT, Epoch Digital (Actis + ADIK), Epsilon Telecommunication (KT Corporation), Equinix, ESDS Data Center, ESR, Etix Everywhere (Genesis Data Center), Everstone, Evolution Data Centres + Central Pattana, Far EasTone Telecommunications, Fir Hills Inc., Firmus & CDC Data Centres, FLOW Digital Infrastructure (PAG), FPT Telecom, Fujitsu, FutureData, G42 (UAE) + FPT + VinaCapital + Viet Thai Group, Gaw Capital (OneHub Saigon), Geraldton Data Centre, GIBO Holdings Ltd., Giga Computing, GigaStream Toyama, Global Digital Management Solutions Pte Ltd, Global Switch, Global Telecommunications (Global Data Centre Sdn Bhd (GDC)), GLP (Ada Infrastructure), Gold Coast Data Centre, Golden TMH Telecom Co., Ltd (GTMH), Goodman, Grand Ming Group (iTech Towers), GreenSquareDC, GSA DATA CENTER, Hanel-CSF, Haoyang Data, HDC Data Center, Henox Data Centers, Hiranandani Group, HITC & Evolution Data Center, HKCOLO, HKT Sky Exchange (HKT Telecommunications), Hong Kong Exchanges and Clearing Limited, Hostway, HT Networks, HTC Telecom International (ECODC), Hyosung Group, i-Berhad, IDC Frontier, IDC Frontier (SoftBank), IGIS Asset Management, IndoKeppel Data Centres, I-NET Corp., Infinaxis Data Centre Holdings (Gaw Capital Partners and A3 Capital), Infracrowd Capital, Integer DC, Interactive, Internet Initiative Japan (IIJ), Internet Thailand, Internetindo Data Centra (IDC Indonesia), Internode Pty Ltd, Inuverse, IPTP Networks, irix Sdn. Bhd., iron Mountain, iseek, ISPT, iTech Tower Data Centre Services, Jakel & PiDC, K2 STRATEGIC, Kakao, KBC – AIC – VietinBank, Kedia Infotech, Keppel DC REIT, Kepstar Data Centre Management, Kingtel Telecom, KINX, KIRZ Data Center Service, KORAMCO Assets Management, Korea Telecom - Jasmine Group, KOSCOM, KT Cloud (Capstone Asset Management), Lao Data Center Co. Ltd, Larsen & Toubro, Leading Edge Data Centres, Lehr Consultants International, LG Uplus, LG, KEPCO, and Hanwha, Localhost, Lotte Innovate, Lumina CloudInfra, Macquarie Data Centres, Macquarie Korea Infrastructure Fund (LG CNS - Customer), Macquarie Telecom Group, MaNaDr, Mapletree Investment Trust, Markham Real Estate Partners, Marunouchi Direct Access, MC Digital Realty, Megaspeed, Megawide Co +Evolution Data Centers, MekongNET, Metavisio Thomson Computing & BKB Energy, MettaDC, Micron21, MIRAIT ONE Corporation, Mitsui Fudosan, Moratelindo Nusantara Data Center (NDC), Myint & Associates Telecommunications Ltd., MyTelehaus, Nautilus Data Technologies + Raimon Land, NES DATA, NetDataVault, netXDC (SCSK), NeutraDC - Nxera & Medco Power, New Generation International, New World Telecommunications Limited (NWT), Nex, NEXTDC, Nextgen Data Centre, NTT Global Data Centers, NTT-TEPCO Power Grid, Nxera (Singtel), Ocean Wave Communication, Okestro, OMNIconnect Broadband Internet and Data Centre (OCDC), On Q Communications, OneAsia Network, Open AI & SK Telecom, Open DC, OPTAGE, Over the wire, Pacific Internet, Perri Projects, Phcolo, Pi Datacenters, PIPE Networks (TPG Telecom), Plan B Limited(Atturra), Polaris, Princeton Digital Group, Proen Internet, Pulse DC Pty Ltd ACN, Pure Data Centres, Qualysite Technologies, Quinbrook Infrastructure Partners, Rack Bank, Racks Central, RailTel Corporation of India Ltd, ReadyIDC, Reliance, Ricoh, RoVision Infrastructure Projects Pvt Ltd, Sabay Digital, Saigon Asset Management (SAM), Saigontel, SAKURA internet, Samsung, Samsung SDS, SC Zeus Data Centers, SEAX Indonesia Pratama, SECOM Trust Systems, SEJONG Networks, SGC Energy, Shinsegae I&C, Sify Technologies, Sinar Primera, Singtel & Telekom Malaysia, SK broadband, SK Ecoplant, DCT Telecom and KB Asset Management, SKYY Development, SM+, ST Engineering, ST Telemedia Global Data Centres, STACK Infrastructure, Starwood Capital Group, Doma Infrastructure Group, and Telstra InfraCo., Stellar DC (Stecon + SC Zeus + Freyr Technology), SUNeVision Holdings (iAdvantage), SunnyVision, SUPERNAP Thailand, Syncom, T4 Group, Taiwan Mobile, Tata Consultancy Services Ltd. (TCS) & OpenAI, TCC Technology, Techno Electric & Engineering (TEECL), Telehouse (KDDI), Teleindia Networks (DataSamudra), Telin Singapore, Telkom Indonesia, Telstra, TenPeaks (Spark Digital), TIS INTEC Group, Towngas Telecommunications Company Limited, Toyota Tsusho Corporation, TPG Angelo Gordon, Trifalga, Trijit Data Centre, True IDC, Umbrellar, United Information Highway (UIH), UPC Volt, USDC Technology, VADS (TM One), Vantage Data Centers, Vector Fibre, Verizon, Viettel, Viettel IDC, VNPT, VNTT, Vocus, VueNow, WHA, Wide Creek Asset Management & PDG, Xtreme Networks`, YCO Cloud Centers, yes seatel, Yondr Group and Marubeni Corporation, YTL Data Center Holdings, ZDATA Technologies (Computility Technology), Zettagrid (DC Two), ZR Power Holdings
SNAPSHOT
INVESTORS/OPERATORS COVERED
(New Era Technology) Intervolve, 5G Networks, AAPT (TPG Telecom), Aboitiz, Acer eDC, AdaniConneX, A-FLOW (Ayala Land and PAG's), AGS Corporation, AIMS Data Centre (DigitalBridge), Airtel (Nxtra), Airtrunk+ ByteDance, AIS Business (CSL), Aizo Group and Netrunner, AkashiQ, AM Green Group (AMG), Anant Raj Cloud Pvt Ltd (ARCPL), AnsonNet, APT Satellite, Aqylon Nexus Limited, Area Group, ARTERIA Networks Corporation, Asia Pacific Land (APL) and Global Compute Infrastructure (GCI), Asia Satellite Telecommunication Company, Aslan Energy Capital, AT TOKYO, Basis Bay, BDx, Beeinfotech, Benzy Infotech Data Center, Bitera Data Center, Bitstop Network Services, Biznet, Blackstone & Panchshil Realty, Bridge Data Centres, BRIGHTRAY, BSNL & NxtGen Datacenter, BW Digital, ByteDC Solutions, C&T + CMC Telecom, Caduceus Systems, Canon IT Solutions, CapitaLand, Carrianna Group, Carrier Connect Data Solutions (Nexion Group), CAT Telecom (National Telecom), CDC Data Centres, Centuria Industrial REIT, Chaktomuk Data Center, Changhae Development, Chief Telecom, China Mobile International, China Unicom, Chinachem Group, Chorus, Chunghwa Telecom, CITIC Telecom International, CloudHQ, CMC Telecom, Colocity, Colt Data Centre Services & ESR joint venture, Computer Concepts Limited (CCL), Converge ICT Solutions Inc., Create Capital Vietnam JSC + Haimaker.ai + Vietnam Data Gen, CSF Group, CTC, CtrlS Datacenters + National Telecom, Cundall Johnston, Currenc Group Inc., Cyber Data International, Cyfuture India, CyrusOne KEP, Da Nang IDC, Daewoo Engineering & Construction, DAMAC Digital, DAOU IDC, Data Center First, Data Centre 220, Data Vault, Datacom Group Ltd, DataGrid, Daun Penh Provider, DayOne (GDS Services), DC Alliance, DC Connect, DC West, DCI Data Centers & Koramco, Digital Connexion (BAM Digital Reality), Digital Edge, Digital Edge DC, Digital Halo, Digital Hyperspace Indonesia, Digital Realty, Digital Sense, Diode Ventures and ENDEC, DITO Telecommunity, Doma Infrastructure Group (DIG), Dongyang (Eugene Group) (Construction to commence 1H 2026), Dreammark1 Corporation, DTP, DTS Telecom, DXN, eASPNet, EasyLink, Edge Centres, EdgeConneX, Elitery Data Center, Empyrion Digital, Enable Networks, Endec Group, ePLDT, Epoch Digital (Actis + ADIK), Epsilon Telecommunication (KT Corporation), Equinix, ESDS Data Center, ESR, Etix Everywhere (Genesis Data Center), Everstone, Evolution Data Centres + Central Pattana, Far EasTone Telecommunications, Fir Hills Inc., Firmus & CDC Data Centres, FLOW Digital Infrastructure (PAG), FPT Telecom, Fujitsu, FutureData, G42 (UAE) + FPT + VinaCapital + Viet Thai Group, Gaw Capital (OneHub Saigon), Geraldton Data Centre, GIBO Holdings Ltd., Giga Computing, GigaStream Toyama, Global Digital Management Solutions Pte Ltd, Global Switch, Global Telecommunications (Global Data Centre Sdn Bhd (GDC)), GLP (Ada Infrastructure), Gold Coast Data Centre, Golden TMH Telecom Co., Ltd (GTMH), Goodman, Grand Ming Group (iTech Towers), GreenSquareDC, GSA DATA CENTER, Hanel-CSF, Haoyang Data, HDC Data Center, Henox Data Centers, Hiranandani Group, HITC & Evolution Data Center, HKCOLO, HKT Sky Exchange (HKT Telecommunications), Hong Kong Exchanges and Clearing Limited, Hostway, HT Networks, HTC Telecom International (ECODC), Hyosung Group, i-Berhad, IDC Frontier, IDC Frontier (SoftBank), IGIS Asset Management, IndoKeppel Data Centres, I-NET Corp., Infinaxis Data Centre Holdings (Gaw Capital Partners and A3 Capital), Infracrowd Capital, Integer DC, Interactive, Internet Initiative Japan (IIJ), Internet Thailand, Internetindo Data Centra (IDC Indonesia), Internode Pty Ltd, Inuverse, IPTP Networks, irix Sdn. Bhd., iron Mountain, iseek, ISPT, iTech Tower Data Centre Services, Jakel & PiDC, K2 STRATEGIC, Kakao, KBC – AIC – VietinBank, Kedia Infotech, Keppel DC REIT, Kepstar Data Centre Management, Kingtel Telecom, KINX, KIRZ Data Center Service, KORAMCO Assets Management, Korea Telecom - Jasmine Group, KOSCOM, KT Cloud (Capstone Asset Management), Lao Data Center Co. Ltd, Larsen & Toubro, Leading Edge Data Centres, Lehr Consultants International, LG Uplus, LG, KEPCO, and Hanwha, Localhost, Lotte Innovate, Lumina CloudInfra, Macquarie Data Centres, Macquarie Korea Infrastructure Fund (LG CNS - Customer), Macquarie Telecom Group, MaNaDr, Mapletree Investment Trust, Markham Real Estate Partners, Marunouchi Direct Access, MC Digital Realty, Megaspeed, Megawide Co +Evolution Data Centers, MekongNET, Metavisio Thomson Computing & BKB Energy, MettaDC, Micron21, MIRAIT ONE Corporation, Mitsui Fudosan, Moratelindo Nusantara Data Center (NDC), Myint & Associates Telecommunications Ltd., MyTelehaus, Nautilus Data Technologies + Raimon Land, NES DATA, NetDataVault, netXDC (SCSK), NeutraDC - Nxera & Medco Power, New Generation International, New World Telecommunications Limited (NWT), Nex, NEXTDC, Nextgen Data Centre, NTT Global Data Centers, NTT-TEPCO Power Grid, Nxera (Singtel), Ocean Wave Communication, Okestro, OMNIconnect Broadband Internet and Data Centre (OCDC), On Q Communications, OneAsia Network, Open AI & SK Telecom, Open DC, OPTAGE, Over the wire, Pacific Internet, Perri Projects, Phcolo, Pi Datacenters, PIPE Networks (TPG Telecom), Plan B Limited(Atturra), Polaris, Princeton Digital Group, Proen Internet, Pulse DC Pty Ltd ACN, Pure Data Centres, Qualysite Technologies, Quinbrook Infrastructure Partners, Rack Bank, Racks Central, RailTel Corporation of India Ltd, ReadyIDC, Reliance, Ricoh, RoVision Infrastructure Projects Pvt Ltd, Sabay Digital, Saigon Asset Management (SAM), Saigontel, SAKURA internet, Samsung, Samsung SDS, SC Zeus Data Centers, SEAX Indonesia Pratama, SECOM Trust Systems, SEJONG Networks, SGC Energy, Shinsegae I&C, Sify Technologies, Sinar Primera, Singtel & Telekom Malaysia, SK broadband, SK Ecoplant, DCT Telecom and KB Asset Management, SKYY Development, SM+, ST Engineering, ST Telemedia Global Data Centres, STACK Infrastructure, Starwood Capital Group, Doma Infrastructure Group, and Telstra InfraCo., Stellar DC (Stecon + SC Zeus + Freyr Technology), SUNeVision Holdings (iAdvantage), SunnyVision, SUPERNAP Thailand, Syncom, T4 Group, Taiwan Mobile, Tata Consultancy Services Ltd. (TCS) & OpenAI, TCC Technology, Techno Electric & Engineering (TEECL), Telehouse (KDDI), Teleindia Networks (DataSamudra), Telin Singapore, Telkom Indonesia, Telstra, TenPeaks (Spark Digital), TIS INTEC Group, Towngas Telecommunications Company Limited, Toyota Tsusho Corporation, TPG Angelo Gordon, Trifalga, Trijit Data Centre, True IDC, Umbrellar, United Information Highway (UIH), UPC Volt, USDC Technology, VADS (TM One), Vantage Data Centers, Vector Fibre, Verizon, Viettel, Viettel IDC, VNPT, VNTT, Vocus, VueNow, WHA, Wide Creek Asset Management & PDG, Xtreme Networks`, YCO Cloud Centers, yes seatel, Yondr Group and Marubeni Corporation, YTL Data Center Holdings, ZDATA Technologies (Computility Technology), Zettagrid (DC Two), ZR Power Holdings
DATA CENTERS IN APAC - FAQ
How many upcoming data center facilities are there in the APAC?
How many countries are covered in the APAC data center market portfolio?
How many existing data center facilities are there in the APAC?
How many data centers are covered in the APAC Data Center Portfolio?
How many operators and investors are covered?
Does the portfolio include colocation pricing?
Which markets account for most of APAC's upcoming data center capacity?
How many operators and investors are covered?
How many data centers are covered in the APAC Data Center Portfolio?
Which markets account for most of APAC's upcoming data center capacity?
Does the portfolio include colocation pricing?
How many operators and investors are covered?
Does the portfolio include colocation pricing?
Which markets account for most of APAC's upcoming data center capacity?
How many data centers are covered in the APAC Data Center Portfolio?
For more details, please reach us at [email protected]
1. ABOUT THE DATABASE
2. SCOPE & ASSUMPTIONS
3. DEFINITIONS
4. SNAPSHOT: EXISTING & UPCOMING DATA CENTER FACILITY
5. EXISTING DATA CENTER DATABASE
6. UPCOMING DATA CENTER FACILITY
7. EXISTING VS UPCOMING CAPACITY (INFOGRAPHICS)
8. COLOCATION PRICING
9. EXPLORE OUR COMPREHENSIVE PORTFOLIO
Select a license type that suits your business needs
ONE TIME SUBSCRIPTION
- Free 10% or 3 days of customization
- Free post-sale service assistance
- Continuous support through email
YEARLY SUBSCRIPTION
- Free updated report every quarter for 1 year
- Free 20% or 6 days of customization
- Free post-sale service assistance
- Continuous support through email and telephone
- Direct access to lead analysts
Frequently Asked Questions
How many upcoming data center facilities are there in the APAC?
How many countries are covered in the APAC data center market portfolio?
How many existing data center facilities are there in the APAC?
How many data centers are covered in the APAC Data Center Portfolio?
How many operators and investors are covered?
Does the portfolio include colocation pricing?
Which markets account for most of APAC's upcoming data center capacity?
How many operators and investors are covered?
How many data centers are covered in the APAC Data Center Portfolio?
Which markets account for most of APAC's upcoming data center capacity?
Does the portfolio include colocation pricing?
How many operators and investors are covered?
Does the portfolio include colocation pricing?
Which markets account for most of APAC's upcoming data center capacity?
How many data centers are covered in the APAC Data Center Portfolio?