Europe HVAC Market Growth Insights – Driven by Steady Construction Activity, Rising Building Renovations, Energy-Efficient HVAC Upgrades, and Growing Demand Across Residential and Non-Residential Infrastructure (2026–2031)
Published Date : June 2026
Last Updated : October 2026
format: PDF
edition : Fifth Edition

236 pages

57 company

7 segments

3 region
23 countries
Purchase Options
Europe HVAC Market Research Report 2026-2031
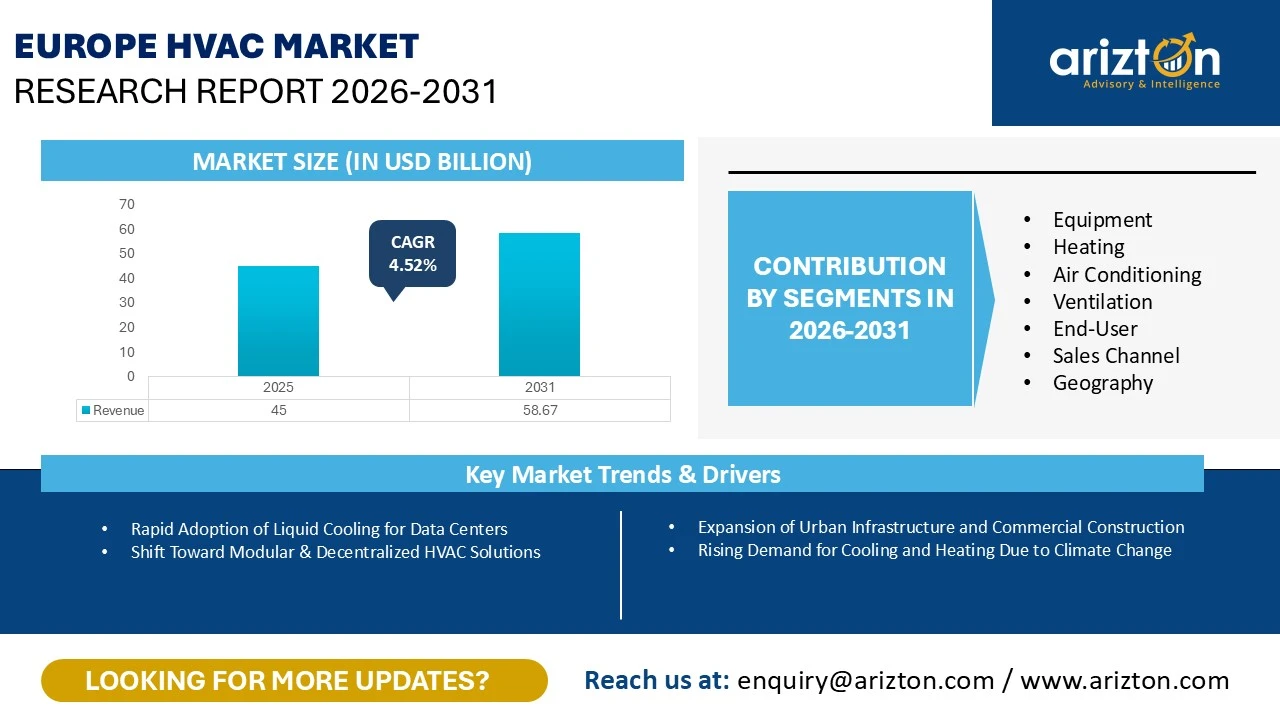
THE EUROPE HVAC MARKET SIZE WAS VALUED AT USD 45 BILLION IN 2025 AND IS EXPECTED TO REACH USD 58.67 BILLION BY 2031, GROWING AT A CAGR OF 4.52% DURING THE FORECAST PERIOD.
The Europe HVAC Market Size, Share & Trends Analysis Report By
- Equipment: Heating, Air Conditioning, and Ventilation
- Heating: Heat Pumps, Boiler Units, Furnaces, and Other Heating Equipment
- Air Conditioning: RAC, CAC, Chillers, VRF/VRV, and Other Air Conditioning Equipment
- Ventilation: AHU, Fan Coil Units, Humidifiers & Dehumidifiers, and Other Ventilation Equipment
- End-User: Residential, Commercial, And Industrial
- Sales Channel: Distributors & Wholesalers, Dealers & Installers, OEM Direct Sales, And Retail & E-Commerce
- Geography: Western Europe (Germany, France, UK, Italy, Spain, Netherlands, Switzerland, Belgium, Austria, Portugal, Greece, and Ireland), Central & Eastern Europe (Poland, Russia, Czech Republic, Romania, Hungary, Slovakia, and Ukraine), and Nordics (Sweden, Norway, Finland, and Denmark)
Industry Analysis Report, Regional Outlook, Growth Potential, Price Trends, Competitive Market Share & Forecast 2026–2031.
This report includes market data points, ranging from trend
analyses to market estimates & forecasts that you can customize
EUROPE HVAC MARKET REPORT SCOPE
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| MARKET SIZE (2031) | USD 58.67 Billion |
| MARKET SIZE (2025) | USD 45 Billion |
| CAGR (2025-2031) | 4.52% |
| HISTORIC YEAR | 2022-2024 |
| BASE YEAR | 2025 |
| FORECAST YEAR | 2026-2031 |
| SEGMENTS BY | Equipment, Heating, Air Conditioning, Ventilation, End-User, Sales Channel, and Geography |
| GEOGRAPHIC ANALYSIS | Western Europe, Nordic, and Central & Eastern Europe (CEE) |
| KEY PLAYERS | Ariston Group, Groupe Atlantic, BDR Therma Group, Carrier, Robert Bosch, Daikin, Glen Dimplex Group, LG Electronics, Mitsubishi Electric Corporation, NIBE Group, Panasonic Group, Samsung, STIEBEL ELTRON, Trane Technologies, and Vaillant Group |
EUROPE HVAC MARKET SIZE & SHARE
The Europe HVAC market size was valued at USD 45 billion in 2025 and is expected to reach USD 58.67 billion by 2031, growing at a CAGR of 4.52% during the forecast period. The market has evolved as a significant component of the region’s building infrastructure and continues to witness steady growth supported by stable new construction activity along with significant replacement and renovation activity across residential and non-residential buildings.
The rapid growth of real estate and infrastructure projects, specifically in economies such as Germany, France, the UK, Spain, the Netherlands, and Poland, is gradually rising the demand for HVAC systems. For instance, projects such as Amsterdam Schiphol Airport in the Netherlands are set to open a major new Pier A in 2027, representing approximately $1.5 billion of expansion aimed at increasing capacity and improving operational efficiency.
The Europe HVAC market is also witnessing a strong shift as governments across the region encourage building decarbonization and electrification initiatives under the European Green Deal and REPowerEU strategy, which increases the replacement of fossil-fuel-based heating systems with energy-efficient heat pumps and low-emission HVAC technologies, thereby significantly supporting the demand for advanced residential and commercial climate-control systems across Germany, France, Italy, the UK, and Nordic countries.
Recent Product Development in the Europe HVAC market
- In 2025, Daikin launched its EWYK-QZ modular air-to-water heat pump at ISH 2025, designed for commercial/industrial applications using low-GWP R-290 (propane) refrigerant.
Mergers & Acquisitions in the Europe HVAC market
- In 2025, Midea Group and Frigicoll announced a joint venture agreement in Spain and France to establish Midea Frigicoll HVAC Spain and Midea HVAC France, expanding their long-running partnership into a new operating model.
- In 2025, Samsung Electronics acquired a Germany-based leading European HVAC solutions provider, FlaktGroup, from private equity firm Triton for approximately $1.7 billion to strengthen Samsung's position in the global data center and commercial cooling markets.
- In 2025, Bosch Group completed the acquisition of Johnson Controls’ residential and light commercial HVAC business on July 31, 2025, for approximately $8 billion.
EUROPE HVAC MARKET TRENDS & DRIVERS
Growing Adoption of AI-Driven Smart HVAC Solutions
The growing adoption of AI-driven smart HVAC solutions is creating new revenue opportunities for manufacturers by improving energy efficiency, reducing operating costs, and enhancing user comfort. Increasing consumer preference for intelligent climate control is accelerating demand for HVAC systems with automated settings, predictive controls, and optimized energy management. Manufacturers are investing in AI-enabled technologies to strengthen product differentiation, improve system performance, and capture a larger share of the evolving European market. For instance, Samsung Electronics introduced its Bespoke AI WindFree Pro air-conditioner range at Mostra Convegno Expocomfort 2026, featuring AI Energy Mode, which analyzes user behavior and environmental conditions to reduce power consumption by up to 30%. Such innovations are expected to support premium product adoption and create opportunities for vendors offering energy-efficient, connected HVAC solutions.
Expansion of Urban Infrastructure and Commercial Construction
The expansion of residential, commercial, and public infrastructure across Europe is generating sustained demand for HVAC equipment. New construction projects require integrated heating, cooling, and ventilation solutions to meet indoor comfort, air quality, and energy efficiency requirements. Large-scale developments, including hospitals, office complexes, transport facilities, and mixed-use buildings, present attractive opportunities for HVAC manufacturers, contractors, and equipment suppliers. For instance, Nantes University Hospital, a major 230,000-square-meter development in France, is expected to be completed by the end of 2026, with full operational opening and the transfer of activities planned for early to mid-2027. Projects of this scale highlight the commercial potential for suppliers of centralized HVAC systems, air handling units, and advanced climate control technologies across Europe's expanding infrastructure sector.
Increasing Renovation Activity and Home Improvement Investments
Europe's aging building stock and growing emphasis on energy efficiency are accelerating demand for HVAC replacement, retrofitting, and modernization projects. Residential property owners, commercial building operators, and institutional facility managers are increasingly investing in high-efficiency heating and cooling equipment to reduce energy consumption, improve indoor comfort, and comply with evolving building performance requirements. The European Commission's Renovation Wave Strategy, launched in 2020, aims to double annual building energy renovation rates by 2030, supporting long-term opportunities for HVAC suppliers. These initiatives are expected to strengthen demand for heat pumps, smart thermostats, efficient ventilation systems, and integrated HVAC upgrades. Manufacturers and distributors offering cost-effective retrofit solutions and installation support are well positioned to benefit from Europe's ongoing building modernization programs.
INDUSTRY RESTRAINTS
High Initial Investment and Installation Costs
High upfront investment remains a significant barrier to HVAC adoption among price-sensitive households and small businesses across Europe. Advanced systems, including heat pumps, variable refrigerant flow (VRF) equipment, and AI-enabled climate control solutions, often require substantial equipment, installation, and system integration expenditure. Residential heating equipment installation costs can range from approximately USD 8,000 to USD 10,000, depending on system capacity, efficiency, and labor requirements. These costs can delay purchasing decisions, particularly among consumers facing budget constraints or limited access to financing. For manufacturers and distributors, offering flexible financing, competitively priced product portfolios, and energy-saving solutions with clear lifecycle cost benefits can help reduce adoption barriers and expand the addressable customer base.
EUROPE HVAC MARKET SEGMENTATION INSIGHTS
INSIGHT BY EQUIPMENT
The Europe HVAC market by equipment is segmented into heating, air conditioning, and ventilation. In 2025, the heating segment accounted for the largest market share, at approximately 50%, supported by Europe's substantial demand for space-heating solutions across residential, commercial, and institutional buildings. The transition toward low-emission heating, stricter energy efficiency requirements, and the replacement of conventional boilers are creating opportunities for manufacturers of high-efficiency heat pumps, hybrid heating systems, and other low-carbon technologies. For instance, Daikin Industries inaugurated a new heat pump production facility in Poland in 2025, strengthening its regional manufacturing capabilities and supporting the supply of heating solutions to European markets.
Within the heating segment, heat pumps accounted for the largest revenue share, driven by building electrification, fossil-fuel boiler replacement, decarbonization commitments, and rising demand for energy-efficient heating systems. Regulatory measures are further supporting market opportunities. Germany's Building Energy Act establishes a requirement for newly installed heating systems to use at least 65% renewable energy under applicable conditions and transition rules, encouraging demand for air-to-water heat pumps and hybrid solutions. Across Europe, subsidies, tax incentives, and financing programs are also helping improve the affordability of heat pump installations. These developments offer manufacturers, distributors, and installers opportunities to expand sales through efficient products, retrofit packages, and end-to-end installation services.
INSIGHT BY AIR CONDITIONING
In 2025, the residential air conditioning (RAC) segment accounted for a significant share of the Europe HVAC market. Rising summer temperatures, increasingly frequent heatwaves, and changing consumer expectations are accelerating demand for residential cooling solutions. Southern Europe remains a key adoption market, while Western and Northern Europe offer additional growth opportunities as air conditioning becomes increasingly important for household comfort. The historically low penetration of residential AC systems across several European markets creates opportunities for manufacturers to expand their customer base through efficient split and multi-split systems designed for different housing types and climatic conditions.
Urbanization and the growing prevalence of apartment-based living are further supporting RAC adoption. Compact residential units, high-density housing developments, and limited indoor space are increasing demand for space-efficient cooling equipment that combines reliable performance with lower energy consumption. Split air conditioners are well positioned to benefit from these requirements because of their installation flexibility and suitability for individual rooms. Demand from property developers, landlords, and residential renovation projects also creates opportunities for suppliers offering quiet operation, smart controls, high energy ratings, and simplified installation. Manufacturers that align product portfolios with European efficiency requirements and evolving household cooling needs can strengthen their competitive position in this expanding segment.
INSIGHT BY VENTILATION
Within the ventilation segment, air handling units (AHUs) accounted for the largest share of the Europe HVAC market. AHUs are integral to centralized HVAC installations across commercial, industrial, and institutional buildings, combining fans, filters, coils, and dampers to deliver conditioned air and maintain indoor environmental quality. Their widespread use in offices, hospitals, airports, educational institutions, and large commercial facilities supports recurring demand for equipment installation, replacement, and upgrades. For manufacturers and suppliers, the segment offers opportunities to serve projects requiring reliable airflow management, energy-efficient operation, and compliance with indoor air quality standards.
Demand for AHUs is further supported by investments in healthcare, education, transport, and commercial infrastructure across Europe. Hospitals require controlled airflow and stringent hygiene management, while airports, universities, and office buildings need ventilation systems capable of managing variable occupancy levels and maintaining consistent indoor comfort. Modernization projects also create opportunities for advanced AHUs featuring energy-efficient fans, heat recovery, smart monitoring, and automated controls. Suppliers offering modular configurations, customized designs, and integrated building management capabilities can target both new construction and retrofit projects, while aftermarket maintenance and component replacement provide additional revenue opportunities.
INSIGHT BY END-USER
Based on end users, the residential segment accounted for the largest share of the Europe HVAC market in 2025, driven by new housing construction, renovation activity, and replacement demand. HVAC systems are essential across single-family homes, apartments, condominiums, duplexes, and residential towers to maintain thermal comfort, indoor air quality, and energy efficiency. Increasing consumer awareness of energy costs and environmental performance is encouraging households to replace aging equipment with advanced heating, cooling, and ventilation solutions. This creates opportunities for manufacturers and installation partners to expand sales through heat pumps, residential air conditioners, smart thermostats, and integrated climate control systems.
The commercial segment is projected to grow at a CAGR of 5.33% during the forecast period, supported by demand for advanced climate control across offices, retail spaces, hotels, hospitals, educational facilities, and other commercial buildings. Building owners and facility managers are increasingly prioritizing energy savings, occupant comfort, ventilation performance, and compliance with building efficiency standards. The adoption of smart building technologies, building automation systems, and energy management solutions is further increasing demand for connected HVAC equipment. Suppliers that offer scalable system configurations, centralized controls, energy optimization capabilities, and lifecycle maintenance services can capitalize on commercial construction and modernization opportunities across Europe.
INSIGHT BY SALES CHANNEL
The Europe HVAC market by sales channel is segmented into distributors and wholesalers, dealers and installers, OEM direct sales, and retail and e-commerce. Distributors and wholesalers accounted for the largest market share in 2025, supported by extensive regional supply networks, established contractor relationships, and the ability to supply a broad portfolio of HVAC equipment, components, spare parts, and aftermarket products. Their role in ensuring product availability, coordinating deliveries, and supporting project execution makes them important partners for manufacturers targeting residential, commercial, and industrial customers across diverse European markets.
Distributors and wholesalers are also becoming increasingly important to Europe's energy transition by connecting manufacturers with installers, contractors, and building owners undertaking heat pump installations and HVAC retrofits. Strong regional inventories, technical product knowledge, and localized service capabilities help distributors respond to changing demand across Germany, France, Italy, and the Nordic countries. For manufacturers, partnerships with established distribution networks can improve market penetration, accelerate product availability, and strengthen customer reach. Distributors that expand their portfolios to include low-emission heating systems, energy-efficient cooling equipment, smart controls, and retrofit components are well positioned to capture additional sales opportunities as Europe's HVAC market shifts toward higher-efficiency technologies.
EUROPE HVAC MARKET GEOGRAPHICAL ANALYSIS
In 2025, Western and Southern Europe are the largest market for the Europe HVAC, accounting for more than 53%. Western and Southern Europe market is driven by strong residential and commercial construction activity, high air-conditioning penetration in Southern Europe, a large installed boiler replacement base, and rapid adoption of heat pumps and energy-efficient HVAC systems across Germany, France, Italy, Spain, and the UK.
The Central and Eastern Europe region is the second-largest market, and Poland dominates the market across the region and accounts for a significant revenue share in 2025, characterized by a strong mix of replacement-driven residential demand and cyclical new construction activities. Moreover, the Nordics is the fastest-growing segment of the Europe HVAC market, supported by the rising hospitality development activities, which are also contributing to incremental HVAC demand across the Nordic region. For instance, hospitality brands are expanding into Sweden through new property openings planned by 2027, reflecting continued investment in premium tourism infrastructure.
EUROPE HVAC MARKET COMPETITIVE LANDSCAPE
The Europe HVAC market is a mature yet rapidly evolving industry, characterized by the presence of multinational HVAC manufacturers, regional heating specialists, and ventilation-focused engineering companies competing across residential, commercial, and industrial applications.
Leading manufacturers such as Daikin, Mitsubishi Electric, Panasonic, LG Electronics, Trane Technologies, and Samsung HVAC maintain strong positions across Europe through broad product portfolios, advanced inverter and heat pump technologies, and extensive distribution and service networks. These companies compete primarily on energy-efficient HVAC systems, VRF technologies, smart controls, and low-GWP refrigerant adoption. For instance, Daikin continues to strengthen its European heat pump manufacturing and R&D footprint, while Panasonic maintains a strong market presence in high-efficiency residential and commercial HVAC systems.
SNAPSHOT
The Europe HVAC market size is expected to grow at a CAGR of approximately 4.52% from 2025 to 2031.
The following factors are likely to contribute to the growth of the Europe HVAC market during the forecast period:
- Expansion of Urban Infrastructure and Commercial Construction
- Rising Demand for Cooling and Heating Due to Climate Change
- Growth in Renovation and Home Improvement Programs
- Implementation of Strict EU Energy and F-Gas Regulations
- Increase in Government Subsidies and Green Financing Programs
Base Year: 2025
Forecast Year: 2026-2031
The report examines the current state of the Europe HVAC market and its market dynamics through 2026−2031. It covers a detailed overview of several market growth enablers, restraints, and trends. The study covers both the demand and supply sides of the market. It also profiles and analyses leading companies and several other prominent companies operating in the market.
Key Vendors
- Ariston Group
- Business Overview
- Product Offerings
- Key Developments
- Key Strategies
- Key Strengths
- Key Opportunities
- Groupe Atlantic
- BDR Therma Group
- Carrier
- Robert Bosch
- Daikin
- Glen Dimplex Group
- LG Electronics
- Mitsubishi Electric Corporation
- NIBE Group
- Panasonic Group
- Samsung
- STIEBEL ELTRON
- Trane Technologies
- Vaillant Group
Other Prominent Vendors
- Aldes
- Business Overview
- Product Offerings
- Alfa Laval
- Biddle Air Systems
- Camfil
- CIAT
- Elco Bruners
- Ferroli
- Gree Electric Appliances, INC.
- LFB Group
- Hisense HVAC
- Midea Group
- Nuaire
- Ostberg
- Riello Group
- Soler & Palau (S&P)
- Swegon
- Trox GMBH
- Clivet
- Vent-Axia
- VTS Group
- Wolf GMBH
- Zehnder Group AG
- Haier HVAC Solutions
- Modine HVAC
- Blue Star Europe B.V.
- H.Stars Group
- GENERAL HVAC Solutions Euro GMBH
- Baxi
- Brink Climate Systems
- Brotje
- Thermoscreens
- Powrmatic
- CoolTherm
- Chiller LTD.
- Dogu Iklimlendirme
- FlowAir
- Cooper&Hunter
- Frico
- Galletti
- HiRef
- Inventor
- Imbat
Segmentation by Equipment
- Heating
- Air Conditioning
- Ventilation
Segmentation by Heating
- Heat Pumps
- Boiler Units
- Furnaces
- Other Heating Equipment
Segmentation by Air Conditioning
- RAC
- CAC
- Chillers
- VRF/VRV
- Other Air Conditioning Equipment
Segmentation by Ventilation
- AHU
- Fan Coil Units
- Humidifiers & Dehumidifiers
- Other Ventilation Equipment
Segmentation by End-User
- Residential
- Commercial
- Industrial
Segmentation by Sales Channel
- Distributors & Wholesalers
- Dealers & Installers
- OEM Direct Sales
- Retail & E-Commerce
Segmentation by Geography
Western Europe
- Germany
- France
- UK
- Italy
- Spain
- Netherlands
- Switzerland
- Belgium
- Austria
- Portugal
- Greece
- Ireland
Central & Eastern Europe
- Poland
- Russia
- Czech Republic
- Romania
- Hungary
- Slovakia
- Ukraine
Nordics
- Sweden
- Norway
- Finland
- Denmark
EUROPE HVAC MARKET FAQs
How big is the Europe HVAC market?
What is the growth rate of the Europe HVAC market?
Who are the major players in the Europe HVAC market?
What are the key trends in the Europe HVAC market?
Which region dominates the Europe HVAC market?
For more details, please reach us at [email protected]
Chapter 1- Scope & Coverage
MARKET DEFINITION
- INCLUSION
- EXCLUSIONS
- MARKET ESTIMATION CAVEATS
MARKET DERIVATION
- MARKET SEGMENTATION BY EQUIPMENT
- MARKET SEGMENTATION BY HEATING
- MARKET SEGMENTATION BY AIR CONDITIONING
- MARKET SEGMENTATION BY VENTILATION
- MARKET SEGMENTATION BY END-USER
- MARKET SEGMENTATION BY SALES CHANNEL
Chapter 2- Premium Insights
Chapter 3- Market Dynamics
INTRODUCTION
- OVERVIEW
- REGULATIONS & SUSTAINABILITY DRIVE EUROPE HVAC MARKET
- INNOVATION DRIVEN BY REGULATION AND ELECTRIFICATION IN THE EUROPEAN HVAC MARKET
- HEAT PUMP MARKET DYNAMICS IN EUROPE
- PROS AND CONS OF SMART HVAC SYSTEMS
MARKET OPPORTUNITIES & TRENDS
- GROWTH OF AI-DRIVEN SMART HVAC ECOSYSTEMS
- RAPID ADOPTION OF LIQUID COOLING FOR DATA CENTERS
- SHIFT TOWARD LOW-GWP REFRIGERANTS & SUSTAINABLE COOLING TECHNOLOGIES
- SHIFT TOWARD MODULAR & DECENTRALIZED HVAC SOLUTIONS
- SURGE IN VRF & HIGH-EFFICIENCY HVAC TECHNOLOGIES
MARKET GROWTH ENABLERS
- EXPANSION OF URBAN INFRASTRUCTURE AND COMMERCIAL CONSTRUCTION
- RISING DEMAND FOR COOLING AND HEATING DUE TO CLIMATE CHANGE
- GROWTH IN RENOVATION AND HOME IMPROVEMENT PROGRAMS
- IMPLEMENTATION OF STRICT EU ENERGY AND F-GAS REGULATIONS
- INCREASE IN GOVERNMENT SUBSIDIES AND GREEN FINANCING PROGRAMS
MARKET RESTRAINTS
- HIGH UPFRONT EXPENDITURE
- SUPPLY-CHAIN INFLATION PRESSURES PROFITABILITY
- SHORTAGE OF SKILLED WORKFORCE
- OEM RE-TOOLING PRESSURE FROM REFRIGERANT TRANSITION UNCERTAINTY
MARKET LANDSCAPE
- MARKET OVERVIEW
- MARKET SIZE & FORECAST
- FIVE FORCES ANALYSIS
- VALUE CHAIN ANALYSIS
CHAPTER 4- MARKET SEGMENTATION
EQUIPMENT (MARKET SIZE & FORECAST: 2022-2031)
- HEATING
- AIR CONDITIONING
- VENTILATION
HEATING (MARKET SIZE & FORECAST: 2022-2031)
- HEAT PUMPS
- BOILER UNITS
- FURNACES
- OTHER HEATING EQUIPMENT
AIR CONDITIONING (MARKET SIZE & FORECAST: 2022-2031)
- RAC
- CAC
- CHILLERS
- VRF/VRV
- OTHER AIR CODITIONING EQUIPMENT
VENTILATION (MARKET SIZE & FORECAST: 2022-2031)
- AHU
- FAN COIL UNITS
- HUMIDIFIERS & DEHUMIDIFIERS
- OTHER VENTILATION EQUIPMENT
END-USER (MARKET SIZE & FORECAST: 2022-2031)
- RESIDENTIAL
- COMMERCIAL
- INDUSTRIAL
SALES CHANNEL (MARKET SIZE & FORECAST: 2022-2031)
- DISTRIBUTOS & WHOLESALERS
- DEALERS & INSTALLERS
- OEM DIRECT SALES
- RETAIL & E-COMMERCE
CHAPTER 5- GEOGRAPHY SEGMENTATION
GEOGRAPHY SEGMENTATION (MARKET SIZE & FORECAST: 2022-2031)
WESTERN & SOUTHERN EUROPE
- GERMANY
- FRANCE
- UK
- ITALY
- SPAIN
- NETHERLANDS
- SWITZERLAND
- BELGIUM
- AUSTRIA
- PORTUGAL
- GREECE
- IRELAND
CENTRAL & EASTERN EUROPE
- POLAND
- RUSSIA
- CZECH REPUBLIC
- ROMANIA
- HUNGARY
- SLOVAKIA
- UKRAINE
NORDICS
- SWEDEN
- NORWAY
- FINLAND
- DENMARK
CHAPTER 6- COMPETITIVE LANDSCAPE
COMPETITIVE LANDSCAPE
- COMPETITION OVERVIEW
- RECENT DEVELOPMENTS
- BUYER DECISION FACTORS
- KEY GROWTH STRATEGIES ADOPTED BY HVAC VENDORS
KEY COMPANY PROFILES
OTHER PROMINENT COMPANY PROFILES
REPORT SUMMARY
- KEY TAKEAWAYS
- STRATEGIC RECOMMENDATIONS
Select a license type that suits your business needs
Single User Licence
- Report accessible by one user only
- Free 10% or 3 days of customization
- Free post-sale service assistance
- Continuous support through email
5 User Licence
- Report accessible by 5 users within the organization
- Free 15% or 4.5 days of customization
- Continuous support through email and telephone
- Free analyst hour
- Free Upgrade: If an updated report published within 180 days of purchase, you will get the revised report free of charge
Corporate Licence
- Free Datasheet worth $1500
- Report accessible by the entire organization
- Free 20% or 6 days of customization
- Free post-sale service assistance
- Continuous support through email and telephone
- Direct access to lead analysts
- Free analyst hour
- Free Upgrade: If an updated report published within 180 days of purchase, you will get the revised report free of charge
Datasheet Licence
- Report accessible by 1 user only
- Free 15% or 32 hours of customization
- Free post-sale service assistance
- Direct access to lead analysts
Frequently Asked Questions
How big is the Europe HVAC market?
What is the growth rate of the Europe HVAC market?
Who are the major players in the Europe HVAC market?
What are the key trends in the Europe HVAC market?
Which region dominates the Europe HVAC market?
Other RELATED Reports

Europe HVAC Maintenance and Services Market - Industry Outlook & Forecast 2024-2029
Published : May 2024

