Indonesia Data Center Portfolio: 130 Facilities, 36 Operators, 11 Locations. Every existing and upcoming data center in Indonesia, profiled by white-floor area, IT load (MW), rack capacity, investment, and colocation pricing.
Published Date : June 2026
Last Updated : September 2026
format: PDF
edition : Ninth Edition
90 Existing Data Centers
40 Upcoming Data Centers
36 Data Center Operators
11 No. of Cities
Purchase Options
Indonesia Existing & Upcoming Data Center Portfolio
INDONESIA DATA CENTER PORTFOLIO: 130 FACILITIES, 36 OPERATORS, 11 LOCATIONS.
Discover Insights on 130 Data Center Facilities Across 11 Key Regions in Indonesia
This database gives you facility-level visibility into Indonesia's colocation data center market — the country with the largest installed base Arizton tracks in Southeast Asia. Instead of market averages, you get:
- Detailed profiles of all 90 existing data centers — operator, address, white-floor area, IT load, rack capacity, Tier standard and year of operation for every facility.
- In-depth analysis of all 40 upcoming projects — investor, planned capacity, investment split, project status and expected year of opening, together adding more than 12.2 million sq ft and 2.4 GW to the market.
- Coverage across 11 key regions — Jakarta, West Java, Central Java, East Java, Banten, Bali, Batam, Kuningan, Riau, South Kalimantan and South Sulawesi — so you can track the shift from Jakarta's established base toward emerging hubs like Batam and Surabaya.
This report includes market data points, ranging from trend
analyses to market estimates & forecasts that you can customize
INDONESIA DATA CENTERS - PORTFOLIO
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Total Facilities Profiled | 130 |
| Existing Data Centers | 90 |
| Upcoming Data Centers | 40 |
| Operators & Investors Covered | 36 |
| Locations Covered | 11 |
| Power Capacity in the Upcoming Pipeline | 2.4 GW+ |
| White-floor Space in the Upcoming Pipeline | White-floor space in the upcoming pipeline |
| Pipeline Planned for Jakarta | 1.5 GW+ |
| Colocation Pricing | Retail & Wholesale |
INDONESIA DATA CENTERS
Indonesia's data center market is expanding around established and emerging digital infrastructure hubs, with Jakarta and West Java accounting for a major concentration of existing facilities. The upcoming pipeline is also substantial, with 40 planned facilities representing more than 12.2 million sq. ft. of space and over 2.4 GW of planned capacity. Jakarta leads the upcoming pipeline with more than 1.5 GW of planned power capacity, while Batam and Surabaya are emerging as secondary markets.
The Indonesia Data Center Portfolio brings these developments together at the facility level, covering capacity, infrastructure, operators, investment, project status, geographic presence, and colocation pricing.
DATA CENTERS IN INDONESIA - MARKET AT A GLANCE
- A large, established base, still adding at scale: 90 facilities are operational today, concentrated mainly in Jakarta and West Java; 40 more are planned, together adding more than 12.2 million sq ft of white-floor space and over 2.4 GW of power capacity.
- Jakarta leads the build-out: Jakarta alone accounts for more than 1.5 GW of the upcoming pipeline's planned power capacity, extending its position as the country's primary hub.
- Capacity leaders today: DCI Indonesia, Telkom Indonesia, and ST Telemedia Global Data Centres are the leading operators by existing capacity.
- Secondary markets are emerging, but well behind: Batam and Surabaya are growing as alternate locations, but remain well behind Jakarta for hyperscale and colocation activity.
- Broad geographic coverage: The portfolio spans 11 locations, including Bali, Batam, Central Java, Jakarta, West Java, Kuningan, Banten, East Java, Riau, South Kalimantan and South Sulawesi.
- A large, established base, still adding at scale: 90 facilities are operational today, concentrated mainly in Jakarta and West Java; 40 more are planned, together adding more than 12.2 million sq ft of white-floor space and over 2.4 GW of power capacity.
- Jakarta leads the build-out: Jakarta alone accounts for more than 1.5 GW of the upcoming pipeline's planned power capacity, extending its position as the country's primary hub.
- Capacity leaders today: DCI Indonesia, Telkom Indonesia and ST Telemedia Global Data Centres are the leading operators by existing capacity.
- Secondary markets are emerging, but well behind: Batam and Surabaya are growing as alternate locations, but remain well behind Jakarta for hyperscale and colocation activity.
- Broad geographic coverage: The portfolio spans 11 locations, including Bali, Batam, Central Java, Jakarta, West Java, Kuningan, Banten, East Java, Riau, South Kalimantan and South Sulawesi.
DATA CENTER FACILITY INTELLIGENCE
Detailed information across Indonesia's existing and upcoming data centers: The portfolio goes beyond a basic list of facilities by tracking the physical, operational, infrastructure, investment, and commercial characteristics of individual data centers.
For existing facilities, the database captures location, address, operator/owner, facility name, white-floor area, IT load capacity, rack capacity, year of operation, Tier standard, and power/cooling redundancy.
For upcoming projects, it captures investor, location, planned area, power capacity, total investment, infrastructure investment split, announcement year, project status, and expected year of opening.
This facility-level structure enables assessment of Indonesia's data center market from both an operational asset and development pipeline perspective.
EXISTING DATA CENTERS IN INDONESIA
Operational facilities with capacity and infrastructure details: the existing facility database provides detailed information on operational data centers across Indonesia, enabling comparison of facility scale, capacity, infrastructure design, location, and operating characteristics.
EXISTING FACILITY DATA POINTS
- Region, city, and facility location
- Full facility address
- Operator/owner name
- Data center/facility name
- Core & shell white-floor area
- Core & shell IT load capacity
- Rack capacity
- Year of operation
- Tier I–IV design standard
- Power redundancy
- Cooling/mechanical redundancy
These fields provide a consistent basis for comparing facility footprint, IT power, rack deployment, design standards, and operational infrastructure.
UPCOMING DATA CENTER PROJECTS IN INDONESIA
Track future capacity, investment, and development status: the upcoming project database provides visibility into Indonesia's expanding data center pipeline, covering announced, planned, and under-construction facilities.
UPCOMING FACILITY DATA POINTS
- Investor name
- Region, city, and project location
- Planned white-floor area
- Planned IT load/power capacity
- Total investment
- Electrical infrastructure investment
- Mechanical infrastructure investment
- General construction investment
- Announcement year
- Project status
- Active or expected year of opening
Track who is investing, where new capacity is being developed, project scale, capital requirements, and expected development timelines.
DATA CENTER OPERATORS & CLOUD PROVIDERS IN INDONESIA
The database covers 36 operators and investors active in Indonesia, from the country's established capacity leaders to global colocation platforms, joint ventures and new entrants.
- Capacity leaders: DCI Indonesia, Telkom Indonesia, ST Telemedia Global Data Centres
- Global and regional colocation platforms: Equinix, Digital Realty Bersama, NTT DATA, Digital Edge (Indonet), Princeton Digital Group, DayOne, EdgeConneX, SpaceDC, Pure Data Centres, BDx Indonesia
- Local and joint-venture operators: Biznet, Datacomm, Moratelindo Nusantara Data Center (NDC), Internetindo Data Centra (IDC Indonesia), Graha Teknologi Nusantara, Metta DC, Bitera Data Center, Elitery Data Center, Cyber Data International, SEAX Indonesia Pratama
- New entrants and specialized investors: DAMAC Digital, BW Digital, Aslan Energy Capital, Gaw Capital Partners & Sinar Primera, IndoKeppel Data Centres, K2 Strategic, LG Sinar Mas, NeutraDC (Singtel & Medco Power), Nex, Triputra Group, DTP, Edge Centres, Digital Hyperspace Indonesia
FULL LIST OF DATA CENTER INVESTORS/OPERATORS IN INDONESIA
Aslan Energy Capital, BDx Indonesia, Bitera Data Center, Biznet, BW Digital, Cyber Data International, DAMAC Digital, Datacomm, DayOne, DCI Indonesia, Digital Edge (Indonet), Digital Hyperspace Indonesia, Digital Realty Bersama, DTP, Edge Centres, EdgeConneX, Elitery Data Center, Equinix, Gaw Capital Partners & Sinar Primera, Graha Teknologi Nusantara, IndoKeppel Data Centres, Internetindo Data Centra (IDC Indonesia), K2 STRATEGIC, LG Sinar Mas, Metta DC, Moratelindo Nusantara Data Center (NDC), NeutraDC - Singtel & Medco Power, Nex, NTT DATA, Princeton Digital Group, Pure Data Centres, SEAX Indonesia Pratama, SpaceDC, ST Telemedia Global Data Centres, Telkom Indonesia, Triputra Group.
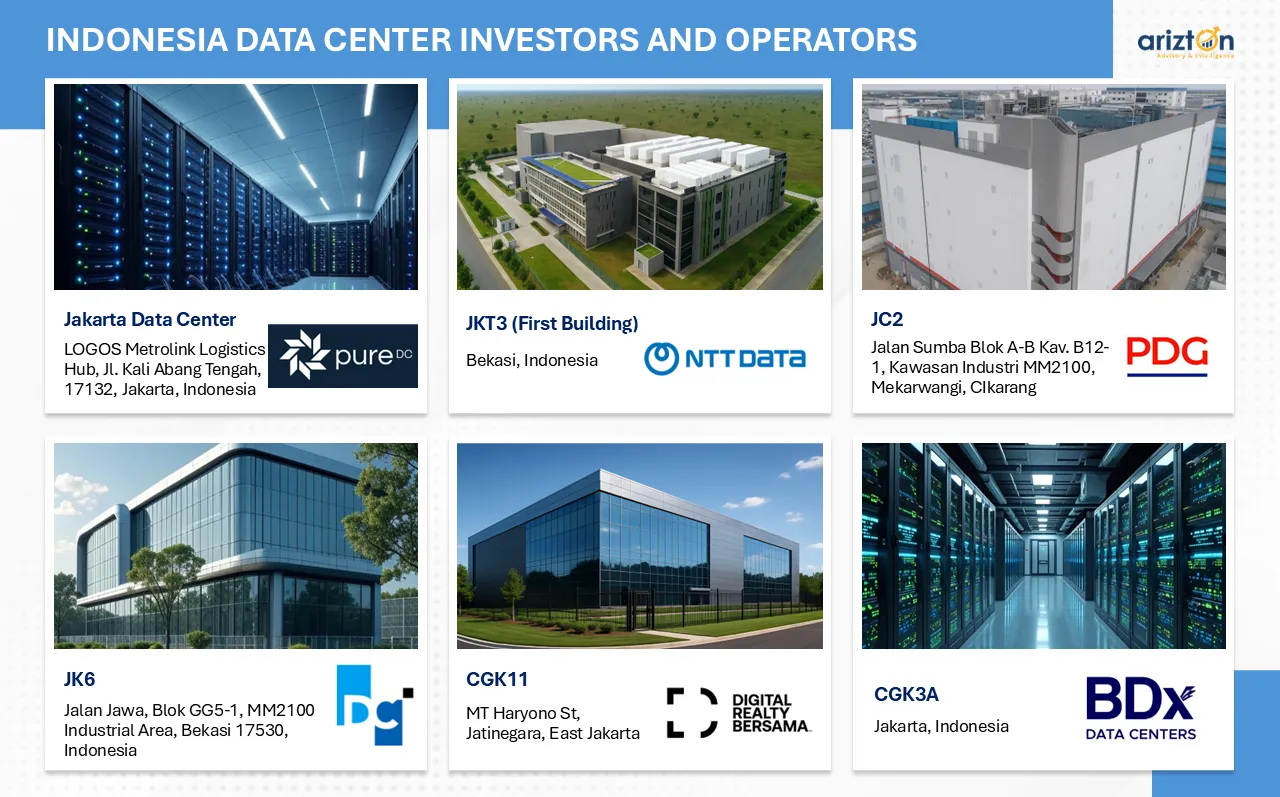
INDONESIA DATA CENTER DEVELOPMENT PIPELINE - 2031
Indonesia's upcoming data center pipeline is adding significant capacity to the country's existing infrastructure base. The portfolio tracks 40 upcoming facilities, with more than 2.4 GW of planned capacity and 12.2+ million sq. ft. of planned space.
Jakarta remains the primary development market, accounting for more than 1.5 GW of planned power capacity. Batam and Surabaya are also developing as secondary markets, providing additional locations for hyperscale and colocation expansion.
GEOGRAPHIC COVERAGE ACROSS INDONESIA
The portfolio covers 11 key locations and regions, providing visibility into the geographic distribution of existing and upcoming data center infrastructure.
LOCATIONS COVERED:
Bali | Batam | Central Java | Jakarta | West Java | Kuningan | Banten | East Java | Riau | South Kalimantan | South Sulawesi
The geographic coverage supports analysis of:
- Established data center clusters
- Emerging development locations
- Operator expansion patterns
- Regional capacity distribution
- Upcoming project activity
- Location-level investment opportunities
DATA CENTER CAPACITY & INFRASTRUCTURE
Facility count alone does not capture the scale of Indonesia's data center market. The portfolio therefore tracks three core facility-level capacity indicators:
- White-Floor Area: Measures the physical IT space available or planned at individual facilities.
- IT Load Capacity: Compare existing and planned IT power capacity in MW.
- Rack Capacity: Assess rack deployment and facility-level infrastructure scale where available.
Together, these metrics provide a clearer view of facility scale, current capacity, and future capacity additions. The database also tracks current IT load and future capacity additions for the 2026–2031 period.
DATA CENTER INFRASTRUCTURE & RESILIENCY
For existing facilities, the database captures infrastructure and resiliency characteristics that help differentiate data centers by design and operational requirements.
Coverage includes:
- Tier I–IV classification
- Electrical/power redundancy
- Mechanical/cooling redundancy
- IT load capacity
- Rack capacity
- White-floor area
- Year of operation
This will help to compare facilities based on capacity, infrastructure configuration, design standards, and resiliency characteristics.
INDONESIA DATA CENTER COLOCATION PRICING
The portfolio includes colocation pricing alongside facility and infrastructure information, enabling users to assess commercial conditions across the Indonesian market.
Coverage includes:
- Quarter rack / 1⁄4 rack pricing
- Half rack cabinet pricing
- Full rack cabinet pricing
- Full cabinet configurations such as 42U / 45U / 47U
- Wholesale colocation pricing per kW
At the broader market level, Indonesia's colocation market is projected to reach USD 1.27 billion by 2031, growing at a 14.36% CAGR from 2025 to 2031. Utilized white-floor area is projected to reach 8.01 million sq. ft., with approximately 198,000 utilized racks and 1,668 MW of utilized IT power capacity by 2031.
WHAT CAN YOU DO WITH THE INDONESIA DATA CENTER PORTFOLIO?
- Identify existing facilities: Build a structured list of operational data centers by city, operator, capacity, and infrastructure characteristics.
- Track upcoming projects: Monitor announced, planned, and under-construction facilities.
- Compare operators: Benchmark operators by facility footprint, IT capacity, rack capacity, and geographic presence.
- Map new investment: Identify where new capital is being directed and which organizations are expanding.
- Assess market capacity: Compare existing and upcoming white-floor area, IT load, and rack capacity.
- Evaluate locations: Identify established and emerging data center markets across Indonesia.
- Benchmark colocation: Compare retail and wholesale pricing across the market.
- Support market entry: Identify relevant operators, investors, locations, projects, and competitive opportunities.
INDONESIA DATA CENTER PORTFOLIO DATABASE COVERAGE - SUMMARY
The database provides structured facility-level information covering:
- Existing Data Centers: 90 facilities with location, address, operator/owner, facility name, white-floor area, IT load, rack capacity, year of operation, Tier standard, and redundancy information.
- Upcoming Data Centers: 40 facilities with investor, location, planned area, IT capacity, investment, infrastructure investment split, announcement year, project status, and expected opening year.
- Commercial Intelligence: Retail and wholesale colocation pricing, including quarter rack, half rack, full rack, and per-kW wholesale pricing.
RESEARCH METHODOLOGY
- Primary sources: data center contractors and subcontractors, system integrators (power, cooling, physical security, fire suppression), developers and infrastructure providers.
- Secondary sources: Arizton monitors 500+ colocation operators across about 50 countries through press releases, annual reports, investor presentations, industry reports, and news.
- Clean counting: phase-wise expansions sit in existing facilities. Ground-up builds sit in upcoming. Campuses count only operational buildings. Capacity colocated inside another provider's facility is not double-counted.
- Actual and estimated values: investment figures blend reported and estimated values, with estimates based on the average data center build cost in Indonesia.
SNAPSHOT
INVESTORS/OPERATORS COVERED
Aslan Energy Capital, BDx Indonesia, Bitera Data Center, Biznet, BW Digital, Cyber Data International, DAMAC Digital, Datacomm, DayOne, DCI Indonesia, Digital Edge (Indonet), Digital Hyperspace Indonesia, Digital Realty Bersama, DTP, Edge Centres, EdgeConneX, Elitery Data Center, Equinix, Gaw Capital Partners & Sinar Primera, Graha Teknologi Nusantara, IndoKeppel Data Centres, Internetindo Data Centra (IDC Indonesia), K2 STRATEGIC, LG Sinar Mas, Metta DC, Moratelindo Nusantara Data Center (NDC), NeutraDC - Singtel & Medco Power, Nex, NTT DATA, Princeton Digital Group, Pure Data Centres, SEAX Indonesia Pratama, SpaceDC, ST Telemedia Global Data Centres, Telkom Indonesia, Triputra Group
INDONESIA DATA CENTERS FAQs
How many upcoming data centers are included in Indonesia?
How many existing data center facilities are there in Indonesia?
How many data centers are profiled in Indonesia?
How many data center operators are covered?
Which data center locations in Indonesia are covered?
What information is available for existing data centers?
Does the portfolio include colocation pricing?
What information is available for upcoming data centers?
What are the key data center markets in Indonesia?
What information is available for existing data centers?
What information is available for upcoming data centers?
How many data centers are profiled in Indonesia?
Which data center locations in Indonesia are covered?
How many data center operators are covered?
Does the portfolio include colocation pricing?
What are the key data center markets in Indonesia?
For more details, please reach us at [email protected]
1. ABOUT THE DATABASE
2. SCOPE & ASSUMPTIONS
3. DEFINITIONS
4. SNAPSHOT: EXISTING & UPCOMING DATA CENTER FACILITY
5. EXISTING DATA CENTER DATABASE
6. UPCOMING DATA CENTER FACILITY
7. EXISTING VS UPCOMING CAPACITY (INFOGRAPHICS)
8. COLOCATION PRICING
9. EXPLORE OUR COMPREHENSIVE PORTFOLIO
Select a license type that suits your business needs
ONE TIME SUBSCRIPTION
- Free 10% or 3 days of customization
- Free post-sale service assistance
- Continuous support through email
YEARLY SUBSCRIPTION
- Free updated report every quarter for 1 year
- Free 20% or 6 days of customization
- Free post-sale service assistance
- Continuous support through email and telephone
- Direct access to lead analysts
Frequently Asked Questions
How many upcoming data centers are included in Indonesia?
How many existing data center facilities are there in Indonesia?
How many data centers are profiled in Indonesia?
How many data center operators are covered?
Which data center locations in Indonesia are covered?
What information is available for existing data centers?
Does the portfolio include colocation pricing?
What information is available for upcoming data centers?
What are the key data center markets in Indonesia?
What information is available for existing data centers?
What information is available for upcoming data centers?
How many data centers are profiled in Indonesia?
Which data center locations in Indonesia are covered?
How many data center operators are covered?
Does the portfolio include colocation pricing?
What are the key data center markets in Indonesia?