

Southeast Asia Data Center Market Landscape 2026-2031
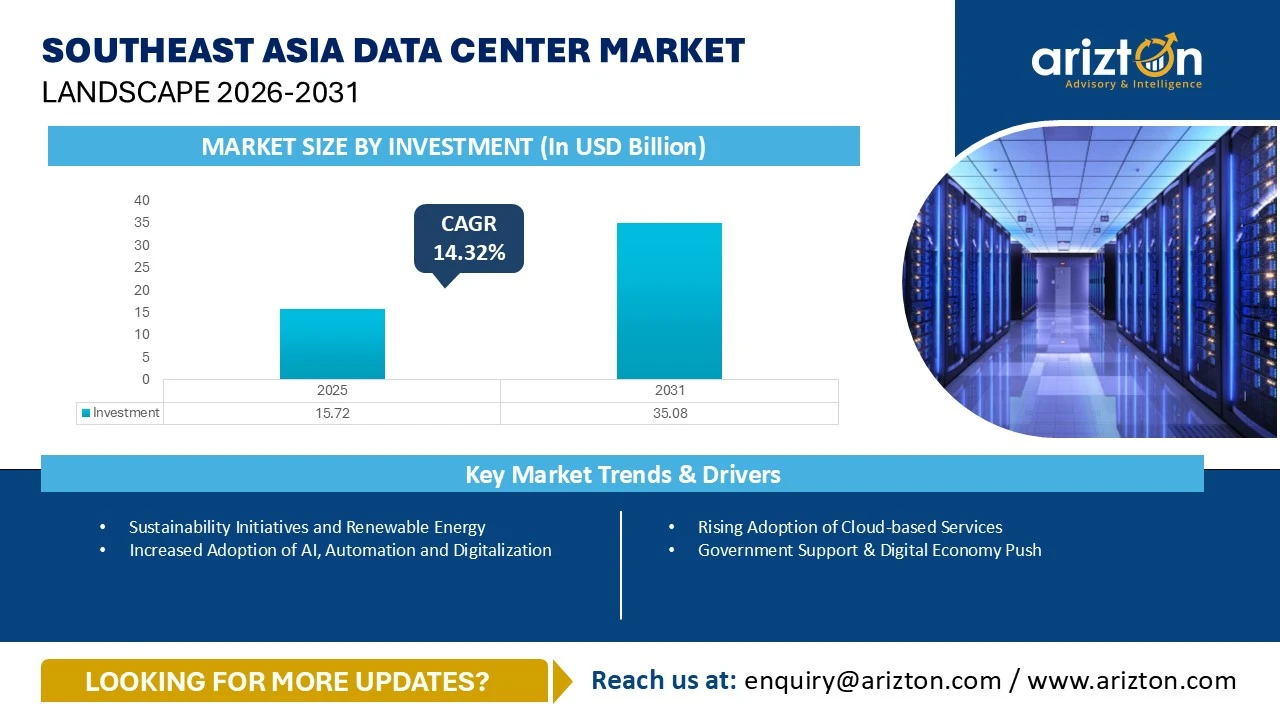
THE SOUTHEAST ASIA DATA CENTER MARKET SIZE WITNESSED INVESTMENTS OF USD 15.72 BILLION IN 2025 AND WILL WITNESS INVESTMENTS OF USD 35.08 BILLION BY 2031, GROWING AT A CAGR OF 14.32% DURING THE FORECAST PERIOD.
The Southeast Asia Data Center Market Size, Share, & Trends Analysis By
- Facility Type: Hyperscale Data Centers, Colocation Data Centers, and Enterprise Data Centers
- Infrastructure: IT Infrastructure, Electrical Infrastructure, Mechanical Infrastructure, and General Construction
- IT Infrastructure: Server Infrastructure, Storage Infrastructure, and Network Infrastructure
- Electrical Infrastructure: UPS Systems, Generators, Transfer Switches & Switchgear, PDUs, and Other Electrical Infrastructure
- Mechanical Infrastructure: Cooling Systems, Racks, and Other Mechanical Infrastructure
- Cooling Systems: CRAC & CRAH Units, Chiller Units, Cooling Towers, Condensers, Dry Coolers, and Other Cooling Units
- Cooling Techniques: Air-based and Liquid-based
- General Construction: Core & Shell Development, Installation & Commissioning Services, Engineering & Building Design, Physical Security, Fire Detection & Suppression, and DCIM
- Tier Standard: Tier I & II, Tier III, and Tier IV
- Geography: Southeast Asia (Singapore, Indonesia, Malaysia, Thailand, Philippines, Vietnam, and Rest of Southeast Asia Countries)
Industry Analysis Report, Regional Outlook, Growth Potential, Price Trends, Competitive Market Share & Forecast 2025–2030.
This report includes market data points, ranging from trend
analyses to market estimates & forecasts that you can customize
SOUTHEAST ASIA DATA CENTER MARKET REPORT SCOPE
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| MARKET SIZE – INVESTMENT (2031) | USD 35.08 Billion |
| MARKET SIZE – INVESTMENT (2025) | USD 15.72 Billion |
| CAGR - INVESTMENT (2025-2031) | 14.32% |
| MARKET SIZE - AREA (2031) | 5.83 Million Square feet |
| POWER CAPACITY (2031) | 1,435 MW |
| HISTORIC YEAR | 2022-2024 |
| BASE YEAR | 2025 |
| FORECAST YEAR | 2026-2031 |
| SEGMENTS BY | Facility Type, Infrastructure, IT Infrastructure, Electrical Infrastructure, Mechanical Infrastructure, Cooling Systems, Cooling Techniques, General Construction, Tier Standard, Geography |
| GEOGRAPHIC ANALYSIS | Singapore, Indonesia, Malaysia, Thailand, Philippines, Vietnam, and Rest of Southeast Asia Countries |
| AI Compute Growth | ~10x by 2030 |
| Area Leader | Malaysia (~2,525K sq ft) |
| Thailand BOI Investment (2025) | $6.7B across 10 new projects |
| Vietnam Renewable Target | 39.2% of energy mix by 2030 |
SOUTHEAST ASIA DATA CENTER MARKET SIZE ANALYSIS
The Southeast Asia data center market is expected to witness significant investment growth, with investments projected to reach USD 15.72 billion in 2025 and increase to USD 35.08 billion by 2031, expanding at a CAGR of 14.32% during the forecast period. The market is expanding rapidly, supported by growing cloud adoption, rising demand for edge computing infrastructure, and the widespread deployment of emerging technologies such as artificial intelligence (AI), big data, and the Internet of Things (IoT). The increasing digitalization of businesses, rising data traffic, and growing demand for high-performance computing infrastructure are further contributing to the development of data center capacity across the region.
The average cost of data center construction in Southeast Asia ranges between USD 7 million and USD 11 million per MW, depending on the country, location, project specifications, and infrastructure requirements. Construction costs remain relatively high due to several factors, including limited availability of suitable land, increasing labor expenses, inflationary pressures, and the need for reliable and scalable power infrastructure. In addition, growing requirements for advanced cooling systems, redundant power infrastructure, and high-quality connectivity are contributing to the overall capital expenditure associated with data center development in the region.
SOUTHEAST ASIA DATA CENTER MARKET BY AREA
The Southeast Asia data center market by area is projected to reach approximately 5.83 million square feet, reflecting the region’s continued expansion as a key digital infrastructure hub. Across Southeast Asia, data center capacity is distributed among several key countries, reflecting varying levels of infrastructure development. Malaysia accounts for a significant share, supported by its expanding data center infrastructure and favorable investment policies. Indonesia also holds a strong position, driven by rapid industrial development and increasing cloud adoption. Meanwhile, emerging markets such as Vietnam and the Philippines are experiencing strong year-on-year expansion, highlighting their growing importance in the regional data center landscape.
SOUTHEAST ASIA DATA CENTER MARKET BY POWER CAPACITY
The Southeast Asia data center market by power capacity is projected to reach approximately 1,435 MW by 2031, reflecting the region’s expanding digital infrastructure and increasing demand for reliable power capacity. Power costs vary widely across Southeast Asian countries, influencing data center location and investment decisions. Singapore has some of the highest electricity rates in the region, driving up operational costs, while Vietnam and Malaysia offer relatively lower power prices, making them more attractive for cost-effective data center development. Meanwhile, Thailand is entering a pivotal phase of power capacity expansion, positioning itself as one of the most dynamic data center markets in Southeast Asia.
KEY TAKEAWAYS
- Facility Type: The colocation data center segment accounted for the largest share of the Southeast Asia data center market, supported by increasing demand for scalable and flexible infrastructure.
- Infrastructure: The IT infrastructure segment held the largest share of the Southeast Asia data center market, driven by the growing need for computing, storage, and networking capabilities.
- IT Infrastructure: The server infrastructure segment dominated the Southeast Asia data center market, accounting for approximately 48% of the market share in 2025.
- Electrical Infrastructure: The UPS systems segment led the Southeast Asia data center market in 2025, reflecting the growing need for reliable backup power and uninterrupted operations.
- Mechanical Infrastructure: Cooling systems represented the largest segment of the Southeast Asia data center mechanical infrastructure market in 2025
- Cooling Systems: Within cooling systems, the CRAC and CRAH segment dominated the Southeast Asia data center market in 2025, supported by their widespread use in maintaining optimal operating temperatures.
- Cooling Technique: The Air-based cooling segment dominated the Southeast Asia data center market in 2025, driven by the increasing adoption of high-density computing and AI workloads.
- General Construction: In 2025, core and shell construction represented the largest segment of the Southeast Asia data center general construction market
- Tier Standard: Tier III facilities dominated the Southeast Asia data center market in 2025, reflecting strong demand for reliable, resilient, and continuously available data center infrastructure.
RECENT DEVELOPMENTS & NEWS IN THE SOUTHEAST ASIA DATA CENTER MARKET
- In May 2025, Huawei and Keppel signed an MoU to jointly develop solar and Battery Energy Storage System (BESS) solutions for data centers and other high-energy sectors across ASEAN. The partnership aims to enhance renewable integration, reduce carbon emissions, and align with Singapore’s Green Plan 2030 through advanced energy management technologies.
- In July 2025, the Southeast Asia–Japan Cable 2 (SJC2) officially went live, five years behind schedule. The SJC2 consortium, along with NEC Corporation, announced the completion and launch of the subsea cable system.
- In September 2025, Seacom announced plans for a 15,534.3-mile cable system linking France, Singapore, and South Africa, featuring 48 fiber pairs and 20 landing points across 15 countries. The system aims to support AI-driven workloads and connect African nations to global digital hubs through open-access and resilient infrastructure.
- In October 2025, Indonesian telecommunications company Telekomunikasi Indonesia International (Telin), and Sarawak Digital Economy Corporation and ITCO Niaga, Malaysian digital infrastructure companies, signed an MoU to jointly develop a subsea cable, Indonesia Cable Express System (ICE) II, stretching from Singapore to Manado, Indonesia.
SOUTHEAST ASIA DATA CENTER MARKET KEY TRENDS
Sustainability Initiatives and Renewable Energy
Data centers are highly energy-intensive facilities and contribute significantly to carbon emissions. However, their environmental impact can be reduced through the adoption of sustainable energy sources, including solar power and green hydrogen. As data storage continues to expand globally, data centers are expected to account for approximately 8% of total energy consumption by 2030, highlighting the need for cleaner and more efficient power solutions.
Indonesia is strengthening its renewable energy efforts as part of its goal to achieve net-zero carbon emissions by 2060. The country aims to generate more than 48% of its electricity from renewable sources by 2030 and is also working toward increasing the share of renewable energy in its electricity mix. In July 2025, NeutraDC partnered with Medco Power, a renewable energy developer, to deploy solar power at its data center facility in Batam, Indonesia. This initiative reflects the growing adoption of renewable energy solutions within Indonesia’s data center industry.
Increased Adoption of AI, Automation and Digitalization
Southeast Asia is witnessing rapid adoption of AI and ML technologies across industries such as finance, healthcare, and logistics, driving increasing demand for high-performance data center infrastructure. As AI computing requirements are expected to grow significantly by 2030, data center capacity across the region is also projected to expand substantially to accommodate rising computational workloads and support ongoing digital transformation.
Thailand is advancing automation and digitalization through various government-led initiatives. The Thailand 4.0 framework supports the development of Smart Cities and Industry 4.0 projects, while the Digital Economy Promotion Agency (DEPA) works with public- and private-sector organizations to accelerate digital technology and IoT adoption. Operating under the Ministry of Digital Economy and Society (MDES), DEPA collaborates with industry stakeholders and agencies, including those under the Ministry of Industry, to promote IoT innovation, digital transformation, and technology-driven economic development.
SOUTHEAST ASIA DATA CENTER MARKET DRIVERS
Rising Adoption of Cloud-based Services
Cloud services are becoming increasingly important across Southeast Asia, supported by the region’s rapidly expanding digital economy, large population, and growing need for scalable and on-demand computing resources. The rapid digitalization of businesses, expansion of e-commerce, increasing adoption of remote and hybrid work, and growing use of AI-driven applications are driving strong demand for cloud infrastructure across the region.
Across several Southeast Asian countries, organizations are accelerating cloud adoption to improve scalability, cost efficiency, operational flexibility, and digital transformation. This trend is further encouraging businesses across industries to migrate workloads and applications to cloud-based platforms.
Government Support & Digital Economy Push
Government policies play a critical role in supporting the development of data center infrastructure across Southeast Asia by promoting streamlined development, energy efficiency, investment, and data sovereignty. As digitalization accelerates across the region, governments are implementing policies and initiatives to strengthen digital infrastructure and create a supportive environment for technology investments.
Governments are increasingly adopting digital-first strategies, including cloud-first policies, e-governance initiatives, and digital skills development programs. In Vietnam, the Vietnam 4.0 framework supports the development of Smart Cities and Industry 4.0 projects, while digital agencies and government bodies work with public- and private-sector stakeholders to promote IoT adoption, digital transformation, and technology-driven development.
SOUTHEAST ASIA DATA CENTER MARKET RESTRAINTS
Power Infrastructure Limitations
Southeast Asia faces significant challenges in maintaining a reliable power supply for data centers as rapid urbanization, rising digital demand, and climate change place increasing pressure on regional energy infrastructure. Prolonged heatwaves in countries such as Vietnam, Malaysia, and Thailand have further strained power grids, contributing to outages and disruptions to critical infrastructure.
Power availability remains one of the major constraints on data center expansion across Southeast Asia. Although demand for cloud services and AI infrastructure continues to grow, several countries face limitations related to grid capacity, power reliability, energy policies, and access to renewable energy. These challenges can affect the pace, location, and cost of new data center development across the region.
Skilled Workforce & Technical Talent Constraints
Southeast Asia faces significant challenges in maintaining a reliable power supply for data centers as rapid urbanization, rising digital demand, and climate change place increasing pressure on regional energy infrastructure. Prolonged heatwaves in countries such as Vietnam, Malaysia, and Thailand have further strained power grids, contributing to outages and disruptions to critical infrastructure.
Power availability remains one of the major constraints on data center expansion across Southeast Asia. Although demand for cloud services and AI infrastructure continues to grow, several countries face limitations related to grid capacity, power reliability, energy policies, and access to renewable energy. These challenges can affect the pace, location, and cost of new data center development across the region.
SOUTHEAST ASIA DATA CENTER MARKET SEGMENTATION INSIGHTS
INSIGHT BY FACILITY TYPE
By facility type, the colocation data center segment dominated the Southeast Asia data center market, supported by strong demand for flexible, scalable, and cost-efficient digital infrastructure. The growing adoption of cloud services, AI, digital applications, and enterprise workloads is encouraging businesses to shift toward colocation facilities, allowing them to access reliable data center infrastructure without the high capital investment associated with building and operating captive facilities.
Colocation providers offer data center space, rack cabinets, power, cooling, connectivity, and other critical infrastructure tailored to customer requirements. The market is broadly divided into retail and wholesale colocation, creating opportunities to serve customers across a wide range of capacity requirements.
Retail colocation is gaining traction among small and medium-sized enterprises, startups, and government organizations seeking flexible infrastructure with lower upfront investments. Meanwhile, wholesale colocation is attracting large enterprises, hyperscale cloud providers, and technology companies requiring substantial capacity and scalable infrastructure. The availability of both models strengthens the value proposition of colocation providers and creates significant opportunities for operators to expand their presence across Southeast Asia.
INSIGHT BY INFRASTRUCTURE
By infrastructure, the IT infrastructure segment held the largest share of the Southeast Asia data center market, driven by rising investments in servers, storage systems, networking equipment, and other mission-critical technologies. The rapid adoption of cloud computing, AI, IoT, big data, and digital services is creating strong demand for high-performance, scalable, and future-ready IT infrastructure across the region.
The continued expansion of hyperscale and colocation facilities is further accelerating investments in advanced IT equipment. Data center operators are increasingly deploying high-density servers, efficient storage systems, and high-speed networking technologies to manage growing data volumes and increasingly complex workloads.
The rapid development of AI applications is creating an additional opportunity for infrastructure vendors, particularly those offering GPU-based computing and high-performance systems. As enterprises and cloud providers increase their AI capabilities, demand for advanced IT infrastructure is expected to remain strong, making this segment an attractive area for technology vendors and data center investors across Southeast Asia.
INSIGHT BY IT INFRASTRUCTURE
By IT infrastructure, the server segment dominated the Southeast Asia data center market, accounting for approximately 48% in 2025. Growth is being supported by increasing demand for high-performance computing, cloud services, AI applications, and scalable digital infrastructure. The rapid increase in enterprise data generation, combined with the expansion of hyperscale and colocation facilities, is encouraging data center operators to invest in next-generation server technologies.
Data centers deploy a range of server configurations, including rack, blade, and tower servers, to address different computing and workload requirements. Rack and blade servers are particularly attractive for large-scale and high-density environments because they provide efficient space utilization, scalability, and strong computing performance.
The growing demand for enterprise, cloud, and data-intensive applications is creating opportunities for leading technology providers, including Cisco Systems, Hewlett Packard Enterprise, Dell Technologies, IBM, Lenovo, and NetApp. Their broad portfolios of server solutions position them to capitalize on the increasing infrastructure requirements of Southeast Asia's rapidly expanding data center ecosystem.
INSIGHT BY ELECTRICAL INFRASTRUCTURE
By electrical infrastructure, the UPS segment held the largest share of the Southeast Asia data center market, reflecting the critical need for uninterrupted power, operational resilience, and business continuity. As data centers support increasingly mission-critical workloads, operators are prioritizing reliable electrical infrastructure capable of protecting IT systems from power interruptions and fluctuations.
UPS vendors are continuously introducing more energy-efficient and high-performance solutions to improve reliability while helping operators manage operating costs. Data center developers are also increasingly adopting advanced redundancy configurations to strengthen infrastructure resilience and maintain continuous operations.
For instance, BDx Data Centers’ SINI facility in Singapore is equipped with UPS systems featuring N+1 redundancy, while NTT DATA’s CBJ6 data center in Cyberjaya, Malaysia, incorporates an N+C block-redundant design with 33 kV power substations. Such deployments highlight the growing focus on resilient electrical infrastructure and create attractive opportunities for UPS, power distribution, and critical power solution providers across Southeast Asia.
INSIGHT BY MECHANICAL INFRASTRUCTURE
By mechanical infrastructure, the cooling systems segment dominated the Southeast Asia data center market in 2025, supported by the region's tropical climate and the increasing heat generated by high-density computing environments. Efficient thermal management has become a critical investment priority as operators seek to maintain performance, reliability, and energy efficiency across expanding data center facilities.
Water-based cooling technologies are widely adopted across Southeast Asia because of their ability to manage high temperatures and support efficient thermal performance. At the same time, new facilities are increasingly incorporating redundant mechanical and electrical systems in line with Uptime Institute Tier standards, strengthening operational reliability and creating opportunities for advanced cooling and infrastructure technology providers.
For instance, the Bangkok Data Center facility developed by ST Telemedia Global Data Centres and Frasers Property Thailand features N+1 redundant chilled water plants and cooling towers. The facility also incorporates CRAH corridors supported by a 2N power supply, providing approximately N+25% redundancy. Such investments demonstrate the increasing emphasis on resilient cooling infrastructure and the expanding opportunity for advanced thermal management solutions in the region.
INSIGHT BY COOLING SYSTEMS
By cooling systems, the CRAC and CRAH segment dominated the Southeast Asia data center market in 2025, driven by the increasing requirement for reliable and precise cooling solutions capable of managing rising heat loads from high-density IT infrastructure.
CRAC and CRAH units remain widely used for precision cooling technologies, supplying conditioned air to data halls and maintaining optimal operating temperatures for critical IT equipment. Their established deployment across data centers, combined with growing computing densities, continues to support demand for advanced precision cooling systems.
Leading operators are increasingly combining chillers with precision cooling technologies to improve thermal performance and operational efficiency. For instance, Equinix’s SG1 data center in Singapore uses CRAC units and water-cooled centrifugal chillers to support efficient cooling and reliable operation of critical IT infrastructure. The continued expansion of high-density data centers is expected to create significant opportunities for cooling technology providers offering energy-efficient and scalable thermal management solutions.
INSIGHT BY COOLING TECHNIQUE
By cooling technique, the air-based cooling segment dominated the Southeast Asia data center market in 2025, supported by its broad applicability and ability to manage increasing thermal loads across different data center environments. Air-based cooling remains an important solution for operators seeking reliable thermal management while adapting cooling systems to facility design, climate, and workload requirements.
Air-based cooling solutions include DX-based CRAC units, free cooling systems, air-cooled chillers, and dry coolers, providing operators with multiple options to balance performance, reliability, and efficiency.
Data center operators are increasingly adopting hybrid cooling configurations based on facility requirements and energy-efficiency objectives. For instance, BDx Data Centers’ CGK4 facility in Jatiluhur, Indonesia, uses water chillers and air-cooled systems to support effective and reliable cooling operations. Such deployments highlight the growing opportunity for cooling solution providers capable of delivering flexible, energy-efficient, and application-specific systems.
INSIGHT BY GENERAL CONSTRUCTION
By general construction, the core & shell development segment dominated the Southeast Asia data center market in 2025, supported by the increasing development of new greenfield facilities across the region. Strong demand for cloud services, AI infrastructure, digital applications, and enterprise computing is encouraging operators to expand capacity, creating substantial opportunities for construction contractors and infrastructure providers.
Land availability is an important consideration in Southeast Asia, particularly in Singapore, where limited land resources are encouraging data center developers to adopt space-efficient and vertical construction approaches. Major technology companies, including Facebook, have adopted vertical data center structures to optimize available land and maximize infrastructure capacity.
The continued pipeline of new data center projects across Southeast Asia is expected to generate opportunities across core and shell construction, engineering, infrastructure development, and related services. As operators accelerate capacity expansion, construction companies with expertise in large-scale and high-density data center projects are well positioned to benefit from the region's infrastructure development cycle.
INSIGHT BY TIER STANDARDS
By tier standards, the tier III segment dominated the Southeast Asia data center market in 2025, driven by the growing requirement for reliable, resilient, and continuously available infrastructure. Tier III facilities provide enhanced redundancy across critical power and cooling systems, enabling operators to conduct maintenance while maintaining operational continuity.
The increasing adoption of tier III standards reflects the growing expectations of enterprises, cloud providers, financial institutions, and other organizations for dependable data center infrastructure. Most new data center projects across Southeast Asia are designed around tier III requirements, with redundant power and cooling systems that can be further enhanced to support higher levels of redundancy as capacity and workload requirements increase.
The continued development of tier III facilities therefore presents strong opportunities for data center developers, engineering contractors, power and cooling equipment providers, and infrastructure technology vendors. As businesses increasingly prioritize uptime, resilience, and service continuity, investment in Tier III-compliant facilities is expected to remain a key feature of Southeast Asia's expanding data center market.
SOUTHEAST ASIA DATA CENTER MARKET GEOGRAPHICAL ANALYSIS
Southeast Asia is becoming a key growth region in the global data center market, supported by rapid digital transformation, cloud adoption, AI deployment, expanding subsea connectivity, and increasing investments in hyperscale and colocation infrastructure. Malaysia, Indonesia, Singapore, Thailand, Vietnam, and the Philippines are the major markets in the region, with each offering distinct opportunities for data center developers, colocation operators, cloud service providers, and infrastructure vendors.
Malaysia
Malaysia should remain a key focus market for companies seeking large-scale data center expansion opportunities in Southeast Asia. The country benefits from its proximity to Singapore, competitive operating costs, favorable digital infrastructure policies, growing AI adoption, and expanding data center ecosystem. Johor is emerging as a particularly attractive investment destination due to its strategic location near Singapore, availability of land, and supporting infrastructure. In September 2025, ZDATA Technologies sought a USD 500 million loan to finance an upcoming data center project in Johor, particularly in the Gelang Patah area near the Singapore border. The continued flow of large-scale investments creates opportunities for data center developers, colocation providers, cloud companies, and critical infrastructure vendors to expand their presence in Malaysia.
Indonesia
Indonesia provides another significant expansion opportunity, with Batam emerging as an attractive data center hub due to its proximity to Singapore and access to multiple power sources, including coal, natural gas, and renewable energy. Companies can target Batam for large-scale hyperscale and colocation developments, supported by its strategic location and improving digital infrastructure. DayOne's development of a new data center campus in Batam, with a combined IT load capacity of approximately 72 MW, demonstrates the scale of opportunity available in the market.
Singapore
Singapore should remain a strategic market for premium data center services and high-value infrastructure solutions. As of December 2025, the country had 45 operational data center facilities providing approximately 5,101.4 thousand sq ft of white floor space, while six upcoming facilities are expected to add around 652.5 thousand sq ft. Although Singapore faces high development costs and significant land constraints, its position as a major digital and connectivity hub creates opportunities for operators offering high-density, energy-efficient, and premium data center infrastructure. Companies can also explore redevelopment and space-optimization opportunities as operators seek to maximize limited industrial land availability.
Thailand
Thailand offers attractive opportunities for international data center developers and colocation providers due to foreign ownership flexibility, access to pre-approved power and fiber infrastructure, and investment incentives through the Eastern Economic Corridor (EEC). Bangkok should remain the primary target market, supported by the presence and expansion of major operators such as ST Telemedia Global Data Centres, AIS Business (CSL), OneAsia Network, True IDC, Internet Thailand, Telehouse, and SUPERNAP Thailand. Companies can leverage Thailand's investment-friendly environment to establish regional colocation facilities and serve growing enterprise, cloud, and digital infrastructure demand.
Vietnam
Vietnam is emerging as a promising market for companies targeting sustainable and digitally driven data center development. The country's focus on renewable energy, digital transformation, AI, and cloud computing is creating new opportunities for data center operators and infrastructure providers. Vietnam's target of achieving net-zero carbon emissions by 2050, along with efforts to increase renewable energy adoption, can support demand for energy-efficient and sustainable data center solutions. The development of a Direct Power Purchase Agreement (DPPA) framework for the data center industry also creates opportunities for operators seeking greater access to renewable electricity and long-term power solutions.
Philippines
The Philippines should also be targeted as an emerging alternative for companies seeking cost-competitive expansion opportunities in Southeast Asia. Its strategic location, growing subsea cable connectivity, government incentives, improving energy infrastructure, and young workforce are strengthening its attractiveness as a regional data center hub. The country's position within the broader APAC network corridor provides opportunities for hyperscale operators, colocation providers, cloud companies, and connectivity providers to expand capacity and serve increasing digital demand.
Overall, Malaysia and Indonesia offer strong opportunities for large-scale capacity expansion, while Singapore provides access to a mature, high-value digital ecosystem. Thailand offers an investment-friendly environment for new facilities, whereas Vietnam and the Philippines present emerging opportunities for companies seeking sustainable, cost-competitive, and long-term regional growth. Data center developers and infrastructure vendors can strengthen their Southeast Asian presence by adopting country-specific investment strategies and targeting markets based on land availability, power infrastructure, connectivity, sustainability requirements, and customer demand.
SOUTHEAST ASIA DATA CENTER VENDORS - LANDSCAPE
The Southeast Asia data center market has the presence of key investors such as Bridge Data Centres, Digital Realty, Equinix, AirTrunk, NTT DATA, Princeton Digital Group, DayOne, ST Telemedia Global Data Centres, Vantage Data Centers, and others.
New Entrants include A-FLOW, Aslan Energy Capital, Beeinfotech PH, BRIGHT RAY, BW Digital, CloudHQ, CtrlS Datacenters, DAMAC Digital, NEXTDC, ZDATA Technologies, STACK Infrastructure and several others.
In the months of May-June of 2025, six new projects were approved by Thailand BOI with a cumulative investment of $3.6 billion (521.2 billion baht). Five among them are the new entrants to the Thailand market, which include Galaxy Data Centers, Galaxy Peak Data Centers, ZDATA Technologies (Stratus Technologies), Vistas Technologies, and Digital Edge DC. The one existing investor is Bridge Data Centers. In November 2025, the Thailand BOI approved four additional data center projects with a total investment of $3.1 billion from Telehouse, ZDATA Technologies, NextGen Data Center and Cloud Services Co., Ltd., a subsidiary of Dubai-based DAMAC Digital and Zenith Data Center and Cloud Services.
The Southeast Asia region continues to witness investment from hyperscalers like Microsoft, Google, AWS, and others. For instance, in Indonesia, Microsoft launched its first data center in May 2025 and is expected to contribute around $2.5 billion to the economy and create 60,000 jobs by 2028. In addition, it will also support digital training for one million people, with 840,000 already participating in AI capability-building.
SNAPSHOT
The Southeast Asia data center construction market size by investment will reach USD 35.08 billion by 2031, growing at a CAGR of 14.32% from 2025 to 2031.
The following factors are likely to contribute to the growth of the Southeast Asia data center construction market during the forecast period:
- Rising Adoption of Cloud-based Services
- Government Support & Digital Economy Push
- Improvement in Connectivity via Submarine Cables
Base Year: 2025
Forecast Year: 2026-2031
The study considers the present scenario of the Southeast Asia data center construction market and its market dynamics for 2026−2031. It covers a detailed overview of several market growth enablers, restraints, and trends. The report offers both the demand and supply aspects of the market. It profiles and examines leading companies and other prominent ones operating in the market.
Segmentation by Facility Type
- Hyperscale Data Centers
- Colocation Data Centers
- Enterprise Data Centers
Segmentation by Infrastructure
- IT Infrastructure
- Electrical Infrastructure
- Mechanical Infrastructure
- General Construction
Segmentation by IT Infrastructure
- Server Infrastructure
- Storage Infrastructure
- Network Infrastructure
Segmentation by Electrical Infrastructure
- UPS Systems
- Generators
- Transfer Switches & Switchgear
- PDUs
- Other Electrical Infrastructure
Segmentation by Mechanical Infrastructure
- Cooling Systems
- Racks
- Other Mechanical Infrastructure
Segmentation by Cooling Systems
- CRAC & CRAH Units
- Chiller Units
- Cooling Towers, Condensers, and Dry Coolers
- Other Cooling Units
Segmentation by Cooling Techniques
- Air-based
- Liquid-based
Segmentation by General Construction
- Core & Shell Development
- Installation & Commissioning Services
- Engineering & Building Design
- Physical Security
- Fire Detection & Suppression
- DCIM
Segmentation by Tier Standard
- Tier I & II
- Tier III
- Tier IV
Segmentation by Geography
- Singapore
- Indonesia
- Malaysia
- Thailand
- Philippines
- Vietnam
- Rest of Southeast Asia Countries
VENDOR LANDSCAPE
Key Data Center IT Infrastructure Providers
- Arista Networks
- Business Overview
- Service Offerings
- Atos
- Broadcom
- Cisco Systems
- Dell Technologies
- Fujitsu
- Hewlett-Packard Enterprise
- Huawei Technologies
- IBM
- Inspur
- Lenovo
- NetApp
- NVIDIA
Key Data Center Support Infrastructure Providers
- ABB
- Business Overview
- Service Offerings
- Aggreko
- Airedale
- Bosch
- Caterpillar
- Cummins
- Cyber Power Systems
- Delta Electronics
- Eaton
- EKG M & E
- Fuji Electric
- HITEC Power Protection
- Johnson Controls
- Legrand
- Mitsubishi Electric
- Narada
- Piller Power Systems
- Rittal
- Rehlko
- Rolls-Royce
- Schneider Electric
- Siemens
- Socomec Group
- Systemair
- STULZ
- TECO Electric & Machinery
- Trane
- Vertiv
- ZTE
Key Data Center Contractors & Subcontractors
- Advance Power Engineering
- Business Overview
- Service Offerings
- AECOM
- AEON SERVICES
- Aesler Grup
- AO Construction
- Apave
- Arcadis
- Archetype Group
- Architects 49
- ARKONIN
- Arup
- Asdi Swasatya
- Asima Architects
- AtkinsRealis
- Aurecon
- AVO Technology
- AWP Architects
- BECA
- B-Global Tech
- Binastra Corporation
- Chaan
- China Construction Industrial & Energy Engineering Group
- Critical Holdings Berhad
- Comfac
- CSF Group
- Cundall
- CTC-Global
- Cyclect Group
- Data Center Design Corporation (DCDC)
- DCD Technology
- DSCO Group
- Design Coordinates
- Exyte (M+W Group)
- Endec Group
- First Balfour
- Finishing Touch Design Studio
- Fortis Construction
- Gamuda
- Gammon Construction
- Gensler
- GCM Technologies
- GreenVeit
- Greatians Consulting
- HSS Engineers
- Infraset
- IJM Corporation
- ISG
- INHERIT TECHNOLOGY ENGINEERING
- Jaya Karya Integrasi
- JSLA Architects
- Jurutera JRK
- Kienta Engineering Construction
- KAJIMA CORPORATION
- LandArc Associates
- Leighton Asia
- Linesight
- LSK Engineering
- Mace
- Meg Consult
- Megawide Construction Corporation
- Meinhardt Group
- MES Group
- Mitrajaya Holdings
- Monocrete
- MN Holdings
- NTT Facilities
- Nakano Corporation
- OWH Consulting
- Parker, van den Bergh
- PKT Quantity Surveyors
- Plan Architect
- PM Group
- PMX Malaysia
- Powerware Systems
- PT Berca Buana Sakti
- PT Jaya Teknik
- PT Jaya Obayashi
- PT AtoZ Teknik
- PT Total Bangun Persada Tbk
- PT PP
- PT Indokoei International
- PT SMI
- PT Sumaraja Indah
- PT Acset Indonusa Tbk
- PPS Group
- PRONET
- QTCG
- Regional Development Consortium (RDC) Arkitek
- Ramboll
- Red Engineering
- Sato Kogyo
- S5 Engineering
- Shaw Architect
- SOL E&C Investment Construction Joint Stock Company
- Sunway Construction Group
- Syska Hennessy Group
- Syntec Construction
- Tarnas
- Taikisha
- Tetra
- Thornton Tomasetti
- Turner & Townsend
- Unique Central
- Universal Smart Data Center Technology (USDC Technology)
- Vale Architects
- VINCI Energies
- WT Asia
Key Data Center Investors
- AIMS Data Centre
- Business Overview
- Service Offerings
- AirTrunk
- AIS Business
- Alibaba Cloud
- Amazon Web Services (AWS)
- BDx Data Centers
- Bitera Data Centers
- Biznet Data Center
- Bridge Data Centres
- China Mobile
- Converge ICT Solutions
- CMC Telecom
- Datacomm Diangraha
- DayOne
- DCI Indonesia
- Digital Edge DC
- Digital Hyperspace Indonesia
- Digital Realty
- DITO Telecommunity
- EdgeConneX
- Elitery
- Empyrion Digital
- ePLTD
- Epsilon Telecommunications
- Equinix
- Etix Everywhere
- FPT Telecom
- Global Switch
- Hanoi Telecom
- IDC Indonesia
- IndoKeppel Data Centres
- Internet Thailand
- Iron Mountain
- K2 Strategic
- Keppel Data Centres
- Mapletree
- MettaDC
- Microsoft
- Nxera
- NTT DATA
- OneAsia Network
- Open DC
- Princeton Digital Group
- Pure Data Centres
- Racks Central
- SM+
- ST Engineering
- ST Telemedia Global Data Centres
- SUPERNAP Thailand
- Telehouse
- Telekom Malaysia (TM)
- Telin Singapore
- Telkom Indonesia (NeutraDC)
- Tencent Cloud
- True Internet Data Center (True IDC)
- Vantage Data Centers
- Viettel IDC
- VNPT
- VNTT
- WHA Group
- YTL Data Center Holdings
NEW ENTRANTS
- A-FLOW
- Business Overview
- Service Offerings
- Aslan Energy Capital (AEC)
- Beeinfotech PH
- BRIGHTRAY
- BW Digital
- CloudHQ
- CtrlS Datacenters
- CURRENC Group
- DAMAC Digital
- Digital Halo
- Diode Ventures
- Doma Infrastructure
- Epoch Digital
- Evolution Data Centres
- FutureData
- Gaw Capital
- Galaxy Data Centers
- Global Telecommunications
- Haoyang Data
- i-Berhad
- Infinaxis Data Centre Holdings
- Infracrowd Capital
- Minoro Energi
- NEXTDC
- SEAX Global
- SC Zeus Data Centers
- Siagon Asset Management
- STACK Infrastructure
- TikTok
- YCO Cloud
- ZDATA Technologies
SOUTHEAST ASIA DATA CENTER MARKET FAQs
How big is the Southeast Asia data center market?
What is the growth rate of the Southeast Asia data center market?
What is the estimated market size in terms of area in the Southeast Asia data center market by 2030?
What are the key trends in the Southeast Asia data center market?
How much MW of power capacity is expected to reach the Southeast Asia data center market by 2030?
For more details, please reach us at [email protected]
1. ABOUT ARIZTON
2. ABOUT OUR DATA CENTER CAPABILITIES
3. WHAT’S INCLUDED
4. SEGMENTS INCLUDED
5. RESEARCH METHODOLOGY
6. MARKET AT GLANCE
7. PREMIUM INSIGHTS
8. INTRODUCTION
9. INVESTMENT OPPORTUNITIES
9.1. INVESTMENT: MARKET SIZE & FORECAST
9.2. AREA: MARKET SIZE & FORECAST
9.3. POWER CAPACITY: MARKET SIZE & FORECAST
10. MARKET DYNAMICS
10.1. MARKET OPPORTUNITIES & TRENDS
10.2. MARKET GROWTH ENABLERS
10.3. MARKET RESTRAINTS
10.4. SITE SELECTION CRITERIA
11. FACILITY TYPE SEGMENTATION
11.1. HYPERSCALE DATA CENTERS
11.2. COLOCATION DATA CENTERS
11.3. ENTERPRISE DATA CENTERS
12. INFRASTRUCTURE SEGMENTATION
12.1. IT INFRASTRUCTURE
12.2. ELECTRICAL INFRASTRUCTURE
12.3. MECHANICAL INFRASTRUCTURE
12.4. COOLING SYSTEMS
12.5. COOLING TECHNIQUES
12.6. GENERAL CONSTRUCTION
13. TIER STANDARDS SEGMENTATION
14. GEOGRAPHY SEGMENTATION
15. SOUTHEAST ASIA
15.1. MARKET SNAPSHOT & KEY HIGHLIGHTS
15.2. DATA CENTER MARKET BY SUPPORT INFRASTRUCTURE
15.3. DATA CENTER MARKET BY IT INFRASTRUCTURE
16. SINGAPORE
16.1. IMPACT OF AI ON THE DATA CENTER INDUSTRY IN SINGAPORE
16.2. GOVERNMENT RULE AND REGULATION FOR DATA CENTER
16.3. MARKET BY INVESTMENT
16.4. MARKET BY AREA
16.5. MARKET BY POWER CAPACITY
16.6. KEY SUPPORT INFRASTRUCTURE ADOPTION
16.7. LIST OF UPCOMING DATA CENTER PROJECTS IN SINGAPORE
17. INDONESIA
17.1. IMPACT OF AI ON THE DATA CENTER INDUSTRY IN INDONESIA
17.2. GOVERNMENT RULE AND REGULATION FOR DATA CENTER
17.3. MARKET BY INVESTMENT
17.4. MARKET BY AREA
17.5. MARKET BY POWER CAPACITY
17.6. KEY SUPPORT INFRASTRUCTURE ADOPTION
17.7. LIST OF UPCOMING DATA CENTER PROJECTS IN INDONESIA
18. MALAYSIA
18.1. IMPACT OF AI ON THE DATA CENTER INDUSTRY IN MALAYSIA
18.2. GOVERNMENT RULE AND REGULATION FOR DATA CENTER
18.3. MARKET BY INVESTMENT
18.4. MARKET BY AREA
18.5. MARKET BY POWER CAPACITY
18.6. KEY SUPPORT INFRASTRUCTURE ADOPTION
18.7. LIST OF UPCOMING DATA CENTER PROJECTS IN MALAYSIA
19. THAILAND
19.1. IMPACT OF AI ON THE DATA CENTER INDUSTRY IN THAILAND
19.2. GOVERNMENT RULE AND REGULATION FOR DATA CENTER
19.3. MARKET BY INVESTMENT
19.4. MARKET BY AREA
19.5. MARKET BY POWER CAPACITY
19.6. KEY SUPPORT INFRASTRUCTURE ADOPTION
19.7. LIST OF UPCOMING DATA CENTER PROJECTS IN THAILAND
20. PHILIPPINES
20.1. IMPACT OF AI ON THE DATA CENTER INDUSTRY IN PHILIPPINES
20.2. GOVERNMENT RULE AND REGULATION FOR DATA CENTER
20.3. MARKET BY INVESTMENT
20.4. MARKET BY AREA
20.5. MARKET BY POWER CAPACITY
20.6. KEY SUPPORT INFRASTRUCTURE ADOPTION
20.7. LIST OF UPCOMING DATA CENTER PROJECTS IN PHILIPPINES
21. VIETNAM
21.1. IMPACT OF AI ON THE DATA CENTER INDUSTRY IN VIETNAM
21.2. GOVERNMENT RULE AND REGULATION FOR DATA CENTER
21.3. MARKET BY INVESTMENT
21.4. MARKET BY AREA
21.5. MARKET BY POWER CAPACITY
21.6. KEY SUPPORT INFRASTRUCTURE ADOPTION
21.7. LIST OF UPCOMING DATA CENTER PROJECTS IN VIETNAM
22. REST OF SOUTHEAST ASIA
22.1. MARKET BY INVESTMENT
22.2. MARKET BY AREA
22.3. MARKET BY POWER CAPACITY
22.4. KEY SUPPORT INFRASTRUCTURE ADOPTION
23. MARKET PARTICIPANTS
23.1. KEY DATA CENTER IT INFRASTRUCTURE PROVIDERS
23.2. KEY DATA CENTER SUPPORT INFRASTRUCTURE PROVIDERS
23.3. KEY DATA CENTER CONTRACTORS & SUBCONTRACTORS
23.4. KEY DATA CENTER INVESTORS
23.5. NEW ENTRANTS
24. QUANTITATIVE SUMMARY
25. APPENDIX
25.1. ABBREVIATIONS
25.2. DEFINITIONS
25.3. SEGMENTAL COVERAGE
Select a license type that suits your business needs
Single User Licence
- Report accessible by one user only
- Free 10% or 3 days of customization
- Free post-sale service assistance
- Continuous support through email
5 User Licence
- Report accessible by 5 users within the organization
- Free 15% or 4.5 days of customization
- Continuous support through email and telephone
- Free analyst hour
- Free Upgrade: If an updated report published within 180 days of purchase, you will get the revised report free of charge
Corporate Licence
- Free Datasheet worth $1500
- Report accessible by the entire organization
- Free 20% or 6 days of customization
- Free post-sale service assistance
- Continuous support through email and telephone
- Direct access to lead analysts
- Free analyst hour
- Free Upgrade: If an updated report published within 180 days of purchase, you will get the revised report free of charge
Datasheet Licence
- Report accessible by 1 user only
- Free 15% or 32 hours of customization
- Free post-sale service assistance
- Direct access to lead analysts
Frequently Asked Questions
How big is the Southeast Asia data center market?
What is the growth rate of the Southeast Asia data center market?
What is the estimated market size in terms of area in the Southeast Asia data center market by 2030?
What are the key trends in the Southeast Asia data center market?
How much MW of power capacity is expected to reach the Southeast Asia data center market by 2030?
Other RELATED Reports
Southeast Asia Data Center Construction Market – Industry Outlook & Forecast 2026-2031
Published : April 2026